In This Article
In the spring of 88 BCE, a geopolitical shock in western Anatolia triggered the first recorded international financial contagion in European history. When King Mithridates VI Eupator of Pontus overran the Roman province of Asia and orchestrated the coordinated massacre of tens of thousands of Roman and Italian residents—an event known to historians as the “Asiatic Vespers”—the panic did not stay confined to the Aegean coast. Within weeks, the destruction of Roman tax-farming syndicates (societates publicanorum) and commercial loan portfolios in Asia paralyzed the banking tables of the Roman Forum. Already strained by the Italian Social War (91–88 BCE), Rome’s credit market seized up so violently that creditors lynched the urban praetor Aulus Sempronius Asellio in broad daylight, the consuls Sulla and Pompeius Rufus imposed emergency interest caps in 88 BCE, and the suffect consul Lucius Valerius Flaccus enacted the radical Lex Valeria de aere alieno of 86 BCE—writing off 75 percent of all outstanding debts across the Republic. [1]
The Social War and the Murder of Praetor Asellio in the Forum (89 BCE)
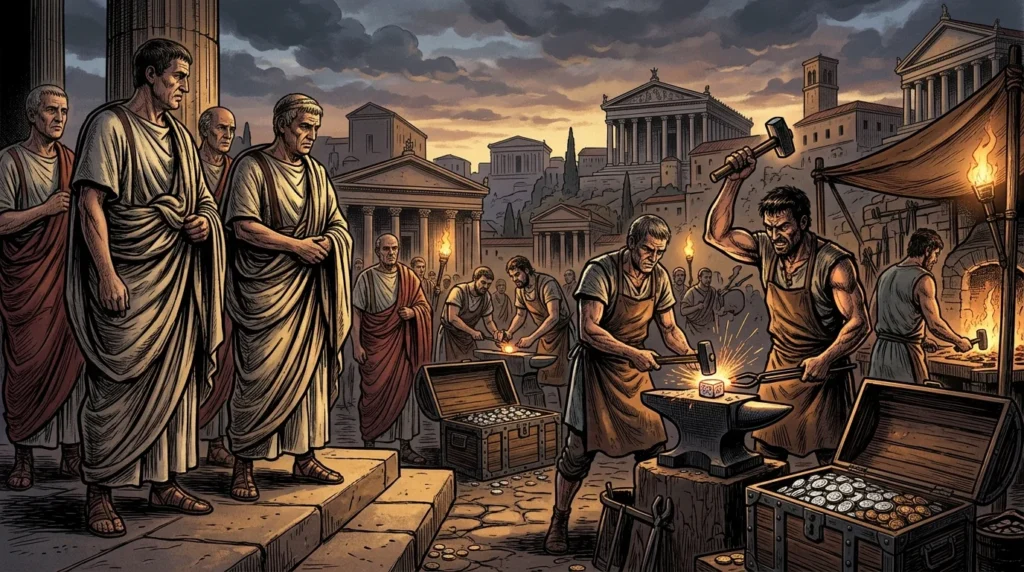
Even before Mithridates crossed the Halys River, Italy’s domestic credit structure was buckling under the fiscal weight of the Social War (91–88 BCE). Fighting against their own revolting Italian allies devastated agricultural estates across Campania, Samnium, and Picenum—the primary real-estate collateral backing senatorial and equestrian loans. As military expenses drained the public treasury (aerarium) and Rome minted debased or emergency silver issues, private moneylenders (faeneratores) called in loans while refusing to roll over maturing obligations, driving land prices into a deflationary spiral. [2]
In 89 BCE, hundreds of insolvent debtors appealed for judicial protection to the urban praetor Aulus Sempronius Asellio, whose court in the Forum held jurisdiction over debt execution. According to the Greek historian Appian in Book I of The Civil Wars, Asellio attempted to mediate the crisis by reviving Rome’s dormant statutory prohibitions against usury—tracing back to the fourth-century BCE Lex Genucia, which had formally forbidden lending at interest among Roman citizens even though custom had long tolerated interest charges. When creditors refused to compromise, Asellio granted debtors legal formulas allowing them to sue their lenders for statutory penalties calculated at quadruple the usurious interest collected. [3]
Enraged that the urban praetor had turned archaic anti-usury laws into an active weapon against their loan books, a faction of creditors led by the plebeian tribune Lucius Cassius organized a brazen assassination. On a morning in 89 BCE, while Asellio—clad in his gold-bordered sacred robe—was pouring a libation at the altar of Castor and Pollux in the middle of the Forum before a crowd of worshippers, a stone was hurled at him. Dropping his sacrificial saucer, the praetor fled toward the Temple of Vesta, but the mob of creditors intercepted him, pursued him into a nearby tavern, and cut his throat. Although the Senate offered cash rewards to free citizens, freedom to slaves, and impunity to accomplices for testimony identifying the killers, the moneylending cartel silenced every witness, and no culprit was ever convicted. [4]
Mithridates’s Invasion of Asia (88 BCE) and Contagion in the Forum
Immediately on the heels of Asellio’s murder came the external shock that turned an Italian liquidity squeeze into a systemic solvency collapse. Since the bequest of the Attalid kingdom of Pergamum to Rome in 133 BCE and Gaius Gracchus’s Lex Sempronia de provincia Asia (123 BCE)—which auctioned the collection of Asian tithes, pasture dues, and customs duties through the censors in Rome—the province of Asia had become the single largest profit center for Roman capital. Joint-stock tax-farming companies (societates publicanorum) bid massive lump sums in Rome to lease Asian tax collection for five-year terms, raising capital from equestrian shareholders (particulae) and borrowing working liquidity from senatorial depositors and Forum bankers (argentarii). Simultaneously, Roman businessmen (negotiatores) lent heavily to Asian municipal governments that needed cash to meet the publicans’ tax demands. [5]
In 88 BCE, Mithridates VI swept through Bithynia and Asia, welcomed by debt-burdened Greek cities as a liberator from Roman tax farmers. On a single prearranged day across Ephesus, Pergamum, Adramyttium, Caunus, and Tralles, local authorities executed every Roman and Italian man, woman, and child—with ancient estimates ranging from 80,000 (Valerius Maximus and Memnon) to 150,000 (Plutarch) killed—and confiscated all Roman-held property and debt contracts. [6]
Two decades later, in 66 BCE, Marcus Tullius Cicero delivered his famous speech De Imperio Cn. Pompei (also known as Pro Lege Manilia), explaining to the Roman assembly exactly how the loss of Asia in 88 BCE had triggered an immediate chain-reaction crash in Rome: [7]
“For, as we learned from what happened at the beginning of the Asiatic War, memory itself teaches us that when many people lost great fortunes in Asia, credit (fides) collapsed at Rome from the delay of payments. For it is impossible for many men in a single state to lose their property and fortunes without dragging even more men along with them into the same catastrophe… Believe me, this system of money and credit which operates at Rome in this Forum is bound up with, and invested in, those Asian revenues; those fortunes cannot be destroyed without undermined credit toppling our own financial system in the very same fall.”
When Asian remittances vanished overnight in 88 BCE, the societates publicanorum defaulted on their obligations to the aerarium and to their private bankers in Rome. Hoarding of silver denarii spiked; anyone holding liquid coin hid it away, real-estate prices plunged as desperate borrowers dumped Italian estates onto a buyerless market, and credit in the Forum froze completely. [8]
Sulla’s Lex Cornelia Pompeia (88 BCE) and the Lex Valeria’s 75% Haircut (86 BCE)
Confronted with simultaneous war in the East and financial paralysis at home, the consuls of 88 BCE—Lucius Cornelius Sulla and Quintus Pompeius Rufus—passed an emergency statute known as the Lex Cornelia Pompeia unciaria. Abandoning the fiction that Roman law prohibited all interest, Sulla and Pompeius re-established the statutory interest ceiling (connecting the archaic unciarium fenus with the Hellenistic monthly rate of centesimae usurae, or 1 percent per month, totaling 12 percent simple interest per year) and granted limited debt remission (removing roughly one-tenth of outstanding principal according to Festus’s surviving lexicon entry). Yet before Sulla’s measure could stabilize the market, civil war erupted between Sulla and the popular faction of Gaius Marius and Lucius Cornelius Cinna.
When Marius and Cinna seized Rome in 87 BCE and Marius died early in his seventh consulship in January 86 BCE, the suffect consul Lucius Valerius Flaccus enacted the most sweeping debt write-down in Roman Republican history: the Lex Valeria de aere alieno of 86 BCE. Rather than abolishing debts outright (tabulae novae), Flaccus restructured every private and public monetary obligation on a two-tier ratio known as the quadrans (one-fourth):
- Seventy-Five Percent Principal Write-Off: Creditors were legally compelled to accept twenty-five percent (one-fourth, or a quadrans) of the nominal principal in full discharge of the loan, wiping out three-quarters of all outstanding debt balances across Roman society.
- Silver Settled with Bronze (Argentum Aere Solutum Est): As the historian Sallust famously summarized in Bellum Catilinae (33) and Velleius Paterculus explained in his Roman History (II.23), debts contracted in silver sestertii (four sestertii to the silver denarius) could be discharged by paying one bronze as for each sestertius owed—effectively settling silver obligations at a 4-to-1 write-down after the recent retariffing of the silver denarius at sixteen bronze asses.
Remarkably, as Cicero later noted in Pro Fonteio, even the Roman state treasury adhered to the Lex Valeria standard in settling public contracts during the 80s BCE, recording payments and receipts in its ledgers at the one-fourth statutory ratio until Sulla returned from the East in 83–82 BCE and restored full silver repayment alongside his proscriptions.
The 12% Centesimae Cap, the Lex Gabinia, and Brutus’s 48% Loan to Salamis
In the aftermath of the Mithridatic wars, Sulla’s exorbitant indemnity of 20,000 talents (120 million silver drachmae) levied on the cities of Asia in 84 BCE reopened the eastern provinces to an even more rapacious wave of Roman lending. Forced to pay cash immediately to Sulla’s troops, Greek cities mortgaged their public theatres, gymnasia, harbor revenues, and Poll taxes to Roman publicani and senatorial financiers at compounding rates that quickly swelled the provincial debt burden to 120,000 talents before Lucius Licinius Lucullus intervened in 71–70 BCE to cap provincial interest at 12 percent annually (centesimae usurae), forbid charging interest on unpaid interest (anatocismus), and cancel interest accruals that exceeded the original principal.
To prevent provincial envoys from borrowing at ruinous rates in the capital itself, the plebeian tribune Aulus Gabinius enacted a second statute in 67 BCE (or during his consulship in 58 BCE)—the Lex Gabinia de versura Romae provincialibus non facienda—which made it illegal for provincial delegations to contract loans in Rome and voided any legal action on such contracts.
How easily Rome’s most celebrated aristocrats circumvented both the 12 percent centesimae ceiling and the Lex Gabinia was laid bare in 51–50 BCE, when Marcus Tullius Cicero served as proconsul of Cilicia (whose jurisdiction included the island of Cyprus). In confidential letters to his friend Titus Pomponius Atticus (Epistulae ad Atticum V.21 and VI.1–2), Cicero recounted his shock upon discovering the true identity behind a predatory loan made in 56 BCE to the Cypriot city of Salamis:
- Senator Behind Straw Men: When Salamis sent envoys to Rome in 56 BCE to borrow money for Roman tax payments, the Lex Gabinia barred them from borrowing. Behind the scenes, Marcus Junius Brutus—nephew of Cato the Younger and later the famous assassin of Julius Caesar—supplied the capital through two equestrian front men, Marcus Scaptius and Publius Matinius, and used his political influence to push two special decrees (senatus consulta) through the Senate exempting the Salamis contract from the Lex Gabinia‘s penalties.
- Forty-Eight Percent Annual Interest (Quaternae Centesimae): Whereas Cicero’s own proconsular edict for Cilicia and Cyprus set the maximum legal rate at 1 percent per month (12 percent per annum, with annual compounding—centesimae renovatae), Brutus’s promissory note (syngrapha) with Salamis charged 4 percent per month (quaternae centesimae), or 48 percent per year, compounded periodically until the debt ballooned from roughly 106 talents to over 200 talents.
- Cavalry Extortion and Starvation of the City Council: Under Cicero’s predecessor Appius Claudius Pulcher (Brutus’s father-in-law), Brutus’s agent Scaptius had been appointed prefect and given a squadron of Roman cavalry in Cyprus. Scaptius used the horsemen to blockade the senators of Salamis inside their own council chamber (curia) so long that five municipal councilors literally starved to death.
When Cicero ordered the cavalry off Cyprus and ruled that Salamis could deposit the principal plus the legal 12 percent interest (totaling 106 talents) in a temple to stop further interest from accruing, both Brutus and Atticus wrote sharp letters pressuring Cicero to enforce the 48 percent bond and give Scaptius fifty cavalrymen. Torn between administrative probity and the patronage demands of his senatorial peers, Cicero refused to grant the troops, prevented Salamis from paying at 12 percent, and left the unresolved 48 percent claim on the books for his successor—exposing how deeply late Republican senatorial fortunes depended on the very provincial debt traps that had repeatedly pushed the Roman world into crisis.
Theoretical & Balance-Sheet Transmission Mechanism
In the Kindleberger–Minsky taxonomy of financial instability (Kindleberger, 1978; Minsky, 1986) and Irving Fisher’s (1933) debt-deflation framework, speculative asset booms become systemic crises when credit expansion shifts balance sheets from hedge finance (cash flows covering principal and interest) to speculative and Ponzi finance (relying on rising asset prices and short-term margin roll-overs).
Once monetary tightening or an exogenous shock halts price appreciation, forced margin liquidations trigger Fisherian debt-deflation: fire-sale asset discounts erode bank collateral values, contracting credit supply across the real economy.
Sources and Further Reading
- Appian of Alexandria, “ The Civil Wars, Book I (Chapter 54: The Debt Crisis of 89 BCE and the Murder of Praetor Aulus Sempronius Asellio),” Loeb Classical Library / LacusCurtius, University of Chicago, 1913. Peer-Reviewed / Academic Research
- Charles Rann Kennedy, “ Fenus,” in William Smith (ed.), A Dictionary of Greek and Roman Antiquities, John Murray, 1875 (LacusCurtius, University of Chicago). Peer-Reviewed / Academic Research
- George Long, “ Publicani,” in William Smith (ed.), A Dictionary of Greek and Roman Antiquities, John Murray, 1875 (LacusCurtius, University of Chicago). Peer-Reviewed / Academic Research
- Classical Association of the Middle West and South (CAMWS), “ The Crisis of 87 BCE: Rome Between the Social and Mithridatic Wars (Financial Crisis, the Asiatic Vespers, and the Lex Valeria of 86 BCE),” CAMWS Annual Meeting Panel, 2013. Historical & Financial Reference
- Michael Hudson and Charles Goodhart, “ Predatory Interest, the Roman Debt Crisis of the 80s BCE, and the Lex Valeria,” Levy Economics Institute Working Paper No. 1058, 2025. Peer-Reviewed / Academic Research
- Peter Temin, “ The Roman Market Economy (Financial Intermediation, Cicero’s Pro Lege Manilia, and Brutus’s Loan to Salamis),” Princeton University Press, 2013. Peer-Reviewed / Academic Research
- Irving Fisher — "The Debt-Deflation Theory of Great Depressions," Econometrica 1, no. 4 (FRASER Federal Reserve Archive, 1933): 337–357 Central Bank / Monetary Authority
- Charles P. Kindleberger & Robert Z. Aliber — Manias, Panics, and Crashes: A History of Financial Crises (Palgrave Macmillan) Peer-Reviewed / Academic Research
Cite This Historical Dossier (APA / Chicago)
APA (7th ed.): Ç., S. (Ed.). (2026). Rome’s Debt Panic: Mithridates, Credit and Brutus’s Loan. In Forgotten Fortunes Historical Monograph Series (Forgotten Fortunes Editorial Desk). https://forgottenfortunes.net/rome-88-bce-debt-crisis-brutus/
MLA (9th ed.): Ç., Soner, ed. "Rome’s Debt Panic: Mithridates, Credit and Brutus’s Loan." Forgotten Fortunes: Financial & Monetary History Archive, 2026, https://forgottenfortunes.net/rome-88-bce-debt-crisis-brutus/.
Chicago (17th ed.): Ç., Soner, ed. "Rome’s Debt Panic: Mithridates, Credit and Brutus’s Loan." Forgotten Fortunes Historical Monograph Series (Forgotten Fortunes Editorial Desk), September 18, 2026. https://forgottenfortunes.net/rome-88-bce-debt-crisis-brutus/.
Have an idea for another financial history documentary or article? Request a story →