In This Article
In the spring of 1584, the banking house of Pisani and Tiepolo—the last surviving private deposit bank operating under the arcades of Venice’s Rialto market—collapsed under more than half a million ducats in liabilities, leaving the Mediterranean’s premier commercial republic without a single transfer bank for three years. For nearly three centuries, Venetian wholesale trade and foreign bills of exchange had cleared through the ledgers of noble-owned private banks (banchi di scritta). Yet as Senator Tommaso Contarini famously warned the Venetian Senate during the landmark banking debates of December 1584, out of roughly one hundred and three private banks founded in Venice over the preceding centuries, ninety-six had ended in bankruptcy, ruin, and depositor panics. [1]

To rescue the Rialto payments system from the inherent fragility of private fractional-reserve banking, the Venetian Senate enacted a historic institutional reform in April 1587, establishing the Banco della Piazza di Rialto—a state-supervised, publicly guaranteed narrow deposit and clearing bank required to hold 100 percent specie reserves against its ledger liabilities. Thirty-two years later, in May 1619, fiscal pressures from military mobilization led the Republic to create a second public institution, the Banco del Giro, which transformed short-term state war debt into an interest-free, universally accepted scriptural currency (ducati di banco) that functioned as Venice’s central monetary pillar until Napoleon dissolved the Republic in 1797. [2]
Why Venice’s Private Rialto Banks Kept Failing (1499–1584)
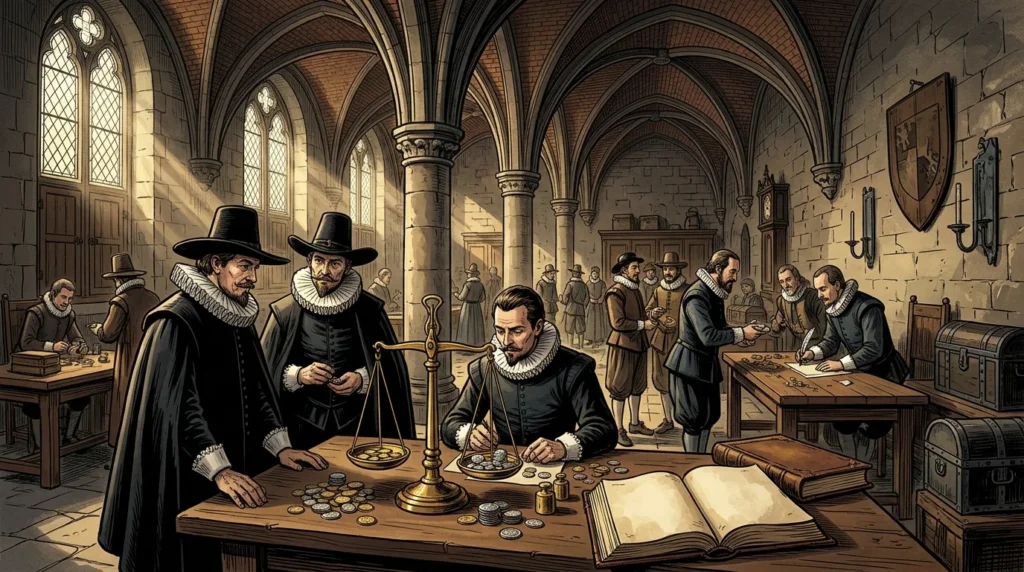
The recurring crises of Venice’s private banchi di scritta stemmed from a structural mismatch between their short-term, on-demand ledger liabilities and their illiquid, high-risk assets. Merchants across Europe deposited gold ducats and silver coin with Rialto bankers not to earn interest, but to gain access to the Rialto giro clearing network—transferring funds instantly by oral instruction (partita di banco) to settle spice cargoes, marine insurance policies, and foreign bills of exchange. Because ledger money was far more convenient than counting and assaying physical coins of varying wear, bank money typically traded at a premium (aggio) over physical currency in ordinary times.
Behind their wooden counters at Campo San Giacomo di Rialto, however, private patrician bankers operated on thin fractional reserves. They invested depositors’ cash in long-distance maritime ventures (colleganze), speculative commodities such as wool, grain, and pepper, real estate, and—most dangerously—large compulsory or negotiated loans to the Venetian Signoria during wars against the Ottoman Empire and Italian rivals. Whenever military defeats, shipwrecked galley fleets, or silver outflows to the Levant tightened liquidity on the Rialto, rumors of insolvency triggered classic bank runs.
The most famous systemic panic struck in January and February 1499, amid the outbreak of the Second Ottoman–Venetian War (1499–1503) and the French invasion of Milan. Within days of one another, the venerable banking house of Andrea Garzoni (whose family bank had operated for seventy years) and the bank of Girolamo Lippomano suffered violent depositor runs. Even after the Venetian state pledged a 10,000-ducat emergency credit line and dramatic scenes unfolded on the Rialto—in which the legendary eighty-year-old former banker Nicolò Bernardo carried bags of gold ducats into the square to lend personally to Garzoni in an effort to calm the crowd—both the Garzoni and Lippomano banks suspended payments, triggering contagious runs on the Agostini and Pisani banks. Further waves of private bank failures followed during the War of the League of Cambrai (1509–1517), in the 1520s, and in the 1570s around the War of Cyprus, culminating in the 1584 failure of the partnership between Alvise Pisani and Lorenzo Tiepolo. [3]
Senator Tommaso Contarini and the 1584–1587 Banking Debates
The collapse of the Pisani-Tiepolo bank in 1584 paralyzed wholesale settlement in Venice. Without a giro bank to clear bills of exchange via book entry, merchants were forced to carry heavy bags of clipped silver and gold coins through the streets or rely on unregulated private IOUs and set-off rings. Inside the Venetian Senate, two opposing camps clashed over how to rebuild the payments architecture. [4]
Advocates of private patrician banking argued that commercial credit issued by private bankers had financed Venice’s merchant marine for centuries and that strict new reserve regulations and higher surety bonds could prevent future collapses. Against them stood Senator Tommaso Contarini, who delivered two celebrated speeches in late 1584 that rank among the earliest theoretical analyses of fractional-reserve banking instability in western economic thought. Contarini demonstrated that private bankers faced an irresistible moral hazard: because they accepted deposits payable on demand at zero interest while bearing the overhead costs of clerks and Rialto booths, they were compelled to lend out or invest the bulk of their vault cash in illiquid mercantile ventures. Yet the moment a war, famine, or trade shock caused merchants to demand physical coin for export, no privately invested bank could liquidate its commercial loans fast enough to survive a run. [5]
If the Republic wanted an unshakeable giro payment medium, Contarini argued, it had to separate the public utility of payment clearing from the private business of speculative lending. Only a public bank guaranteed by the Venetian state—strictly forbidden from making private loans or investing in merchandise, and holding 100 percent of its deposits in physical specie inside public vaults—could enjoy absolute confidence. [6]
The 1587 Banco della Piazza di Rialto: Europe’s First Narrow Giro Bank
After three years of commercial disruption without a bank, the Venetian Senate adopted Contarini’s blueprint on April 11, 1587, enacting the statute that established the Banco della Piazza di Rialto (the Bank of the Rialto Square). Housed under the porticos of San Giacomo di Rialto and overseen by a Senate magistracy, the Provveditori sopra Banchi, the new institution was farmed out in three-year administrative terms to a bonded governor (governatore) selected by the Senate, whose operations were fully guaranteed by the Republic of Venice. [7]
By statute, the Banco della Piazza di Rialto operated as a pure 100-percent-reserve deposit and transfer bank: [8]
- Strict Prohibition on Lending: Neither the bank governor nor its bookkeepers were permitted to lend a single ducat to private merchants or to the state, nor could any depositor overdraw his ledger account.
- Full Convertibility on Demand: Every account holder had the unconditional right to withdraw his balance in full-weight physical gold or silver coin at any time without fee.
- Compulsory Clearing of Bills of Exchange (1593): To anchor the bank at the center of international trade and eliminate settlement in clipped or counterfeit coin, the Senate decreed in December 1593 that all commercial bills of exchange (lettere di cambio) drawn on or payable in Venice had to be settled exclusively by book-entry transfer (in partita di banco) at the Rialto Bank, rendering cash payments for bills legally invalid.
To fund the bank’s administrative salaries without lending out reserves, the Republic earmarked customs duties and state revenues. The Banco della Piazza di Rialto proved an immediate operational success, attracting nearly one million ducats in deposits within a decade and serving directly as the institutional model for the Amsterdam Wisselbank (founded in 1609), the Bank of Hamburg (1619), and the Bank of Nuremberg (1621).
The 1619 Banco del Giro and the Monetization of State Debt
While the 1587 Rialto Bank solved the problem of private bank runs by outlawing credit creation, its strict 100-percent-reserve mandate left the Venetian state without a mechanism to finance sudden military deficits. Between 1615 and 1618, the Republic fought the costly Uskok War (War of Gradisca) against Habsburg Austria while maintaining naval squadrons across the Adriatic and Mediterranean. To pay mercenaries and purchase silver bullion and grain from major merchant suppliers—most notably the silver merchant Giovanni Vendramin—the Venetian Mint (Zecca) issued large volumes of short-term payment orders (fedi di credito) that accumulated in arrears as the Mint ran short of coined specie.
In May 1619, the Venetian Senate created a second, separate public institution—the Banco del Giro (“Bank of the Circulation” or Giro Bank)—specifically designed to monetize these floating state liabilities. Instead of paying state creditors immediately in physical silver coin, the Republic credited them with transferable book-entry balances (partita di banco) at the new Banco del Giro, backed by a dedicated reserve fund of 150,000 (quickly raised to over 250,000) ducats in the Mint and monthly silver allocations of 10,000 to 30,000 ducats from tax revenues. Crucially, the Senate declared ledger credits at the Banco del Giro legal tender for settling bills of exchange alongside the older Rialto Bank and prohibited anyone from refusing payment in Banco del Giro book entries.
Because the Venetian Treasury routed all major state payments, customs settlements, and bullion purchases through the Banco del Giro, network effects rapidly pulled private merchants away from the older Banco della Piazza di Rialto. By the early 1630s, following the devastating Italian plague of 1629–1631 (during which the Banco del Giro expanded its ledger balances to over 2.6 million ducats to keep state finances afloat), deposits at the older 1587 Rialto Bank dwindled so severely that the Senate formally liquidated the Banco della Piazza di Rialto in 1637, leaving the Banco del Giro as Venice’s sole public bank.
Denominated in an invariant accounting currency—the ducato di banco, fixed by law at 20 percent above the circulating currency ducat (ducato corrente)—the Banco del Giro alternated over the next century and a half between periods of full specie convertibility (cassa aperta, “open cash desk”) during peacetime and temporary suspensions of convertibility (cassa chiusa, “closed cash desk”) during major fiscal shocks such as the War of Candia against the Ottomans (1645–1669) and the War of the Spanish Succession. By combining state-guaranteed giro clearing with flexible debt monetization, Venice’s twin public banks of 1587 and 1619 bridged the transition from medieval moneychangers’ booths to early modern central banking.
Theoretical & Balance-Sheet Transmission Mechanism
In the Kindleberger–Minsky taxonomy of financial instability (Kindleberger, 1978; Minsky, 1986) and Irving Fisher’s (1933) debt-deflation framework, speculative asset booms become systemic crises when credit expansion shifts balance sheets from hedge finance (cash flows covering principal and interest) to speculative and Ponzi finance (relying on rising asset prices and short-term margin roll-overs).
Once monetary tightening or an exogenous shock halts price appreciation, forced margin liquidations trigger Fisherian debt-deflation: fire-sale asset discounts erode bank collateral values, contracting credit supply across the real economy.
Sources and Further Reading
- William Roberds and François R. Velde, “Early Public Banks (Working Paper No. 2014-9),” Federal Reserve Bank of Atlanta / EconStor, 2014. Central Bank / Monetary Authority
- Charles Goodhart, William Roberds, and Albrecht Ritschl, “Pandemic, Recession, and Helicopter Money: Venice, 1629–1631,” Cambridge University Press (Financial History Review), 2021. Peer-Reviewed / Academic Research
- Donato Masciandaro, Davide Romelli, and Stefano Ugolini, “Fiscal Dominance, Monetary Policy and Exchange Rates: Lessons from Early Modern Venice,” Sveriges Riksbank Monetary and Financial History Conference, 2024. Central Bank / Monetary Authority
- Stefano Ugolini, “What Do We Really Know about the Long-Term Evolution of Central Banking?,” Yale University Economic History Workshop, 2011. Peer-Reviewed / Academic Research
- Charles F. Dunbar, “The Bank of Venice,” The Quarterly Journal of Economics (Harvard University, Vol. 6, No. 3), 1892. Peer-Reviewed / Academic Research
- Reinhold C. Mueller, “Monete e banche a Venezia (Storia di Venezia),” Istituto della Enciclopedia Italiana Treccani, 1997. Historical & Financial Reference
- Irving Fisher — "The Debt-Deflation Theory of Great Depressions," Econometrica 1, no. 4 (FRASER Federal Reserve Archive, 1933): 337–357 Central Bank / Monetary Authority
- Charles P. Kindleberger & Robert Z. Aliber — Manias, Panics, and Crashes: A History of Financial Crises (Palgrave Macmillan) Peer-Reviewed / Academic Research
Cite This Historical Dossier (APA / Chicago)
APA (7th ed.): Ç., S. (Ed.). (2026). Rialto Bank Runs, the 1587 Banco di Rialto, and the 1619 Banco del Giro. In Forgotten Fortunes Historical Monograph Series (Forgotten Fortunes Editorial Desk). https://forgottenfortunes.net/venice-1587-banco-di-rialto/
MLA (9th ed.): Ç., Soner, ed. "Rialto Bank Runs, the 1587 Banco di Rialto, and the 1619 Banco del Giro." Forgotten Fortunes: Financial & Monetary History Archive, 2026, https://forgottenfortunes.net/venice-1587-banco-di-rialto/.
Chicago (17th ed.): Ç., Soner, ed. "Rialto Bank Runs, the 1587 Banco di Rialto, and the 1619 Banco del Giro." Forgotten Fortunes Historical Monograph Series (Forgotten Fortunes Editorial Desk), September 13, 2026. https://forgottenfortunes.net/venice-1587-banco-di-rialto/.
Have an idea for another financial history documentary or article? Request a story →