In This Article
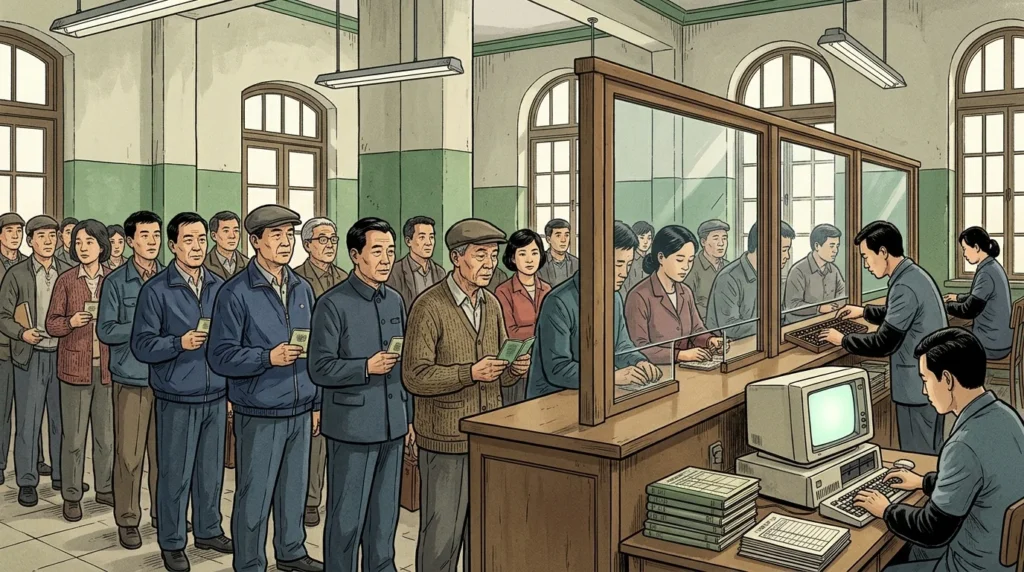
In the ninth lunar month of 1069, under the patronage of the twenty-one-year-old Emperor Shenzong, Northern Song Chief Councillor Wang Anshi promulgated the Green Sprouts Law (Qingmiaofa), one of the most ambitious experiments in state-administered rural microcredit and public debt management in premodern world history. Designed as the fiscal cornerstone of Wang Anshi’s sweeping New Policies (Xinfa), the statute converted the cash and grain reserves of the empire’s Ever-Normal Granaries (Changpingcang) and Liberal Charity Granaries (Guanghuicang) into a revolving rural development bank. Twice each year—in the first or second lunar month when winter stores ran out and rice shoots were still “green sprouts” in the paddies, and again in the fifth month—prefectural and county magistrates lent cash or grain to peasant households, collecting the principal plus a statutory 20 percent interest surcharge after the summer and autumn harvests. [1]

Three years later, in 1072, Wang Anshi extended state credit intervention from the countryside to the imperial capital of Kaifeng and major commercial cities through the Market Exchange Law (Shiyifa), which offered inventory-collateral loans at 10 percent semiannual interest (or 20 percent annually) to urban merchants previously reliant on private usurers and Buddhist monastery pawnshops (Changshengku). Yet what Wang Anshi envisioned as a benevolent fiscal mechanism that would simultaneously rescue smallholders from predatory landlords and replenish the imperial treasury without raising land taxes rapidly mutated on the ground. Evaluated on their loan-collection targets, county magistrates imposed compulsory borrowing quotas (yipei) on wealthy and indigent households alike, sparking a generational ideological war with the conservative historian Sima Guang that culminated in the repeal of the New Policies in 1085–1086. [2]
The Rural Usury Crisis and Monastic Pawnshops (Changshengku)
By the mid-eleventh century, the Northern Song Dynasty (960–1127 CE) faced a structural fiscal crisis despite presiding over an unprecedented commercial boom. Defense expenditures along the northern and northwestern frontiers against the Khitan Liao Empire and the Tangut Western Xia state—which absorbed more than 80 percent of central government revenue to maintain a standing professional army of over 1.25 million soldiers—left the imperial treasury in chronic deficit. At the same time, the monetization of Song taxation increasingly required peasant households to pay seasonal obligations in copper cash strings (guan) or silver rather than solely in grain and silk. [3]
In the Chinese countryside, the agricultural calendar created a severe seasonal liquidity trap. Between the late winter planting season and the autumn harvest, smallholder families and tenant farmers routinely exhausted their seed grain and copper coins. To survive the lean spring months, peasants were forced to borrow from wealthy manorial landlords (haomin), urban pawnbrokers, or Buddhist monastic treasuries known as “Long-Life Treasuries” (Changshengku) and collateral pawnshops (didangku). Drawing on tax-exempt temple endowments and lay investor syndicates, monastic pawnshops and private rural lenders routinely charged compound interest rates of 50 to 100 percent over a single six-month growing season—and up to 100 to 200 percent annualized—despite nominal Song legal ceilings capping private interest at 3 to 4 percent per month and prohibiting total interest from exceeding the original principal (yiben yili). When autumn harvest prices dropped, indebted peasants defaulted in droves, forfeiting their land deeds to tax-evading estates and eroding the imperial tax base. [4]
The Mechanics of the 1069 Green Sprouts Act (Qingmiaofa)
Inspired by his earlier tenure as a local magistrate in Yin County (modern Ningbo, Zhejiang), where he had successfully lent official granary reserves to local farmers at modest interest, Wang Anshi established the Finance Planning Commission (Zhi置 Sansi Tiaolisi) in early 1069 and issued the empire-wide Green Sprouts Law in September 1069. To capitalize the new credit system, the state transferred roughly 15 million strings of copper cash and grain from the Ever-Normal Granaries into circuit-level stabilization funds overseen by Fiscal Intendants (Tiju Changpingguan). [5]
Under the statutory rules of the Qingmiaofa, rural borrowers were organized into mutual-responsibility guarantee groups (bao) of five to ten households, with wealthier landowning households required to act as guarantors for poorer neighbors. Loans were disbursed in two seasonal tranches—the spring lending in the first or second lunar month and a summer lending in the fifth month—and repaid alongside the semiannual land tax in the sixth and tenth lunar months. Wang Anshi fixed the statutory interest rate (termed “transport and wastage fee,” haomi, by supporters to avoid the Confucian stigma of state usury) at 20 percent per six-month lending cycle, though local circuits sometimes collected up to 30 percent to cover grain conversion losses. If a borrower borrowed copper cash in spring when grain was expensive and repaid in grain in autumn when harvest prices plummeted, the law stipulated that conversion valuations be set near market averages so peasants would not be crushed by seasonal price swings. [6]
Urban Credit Expansion: The 1072 Market Exchange Bureau (Shiyiwu)
Having nationalized a large share of rural seasonal credit, Wang Anshi turned in the third lunar month of 1072 to urban commercial credit and wholesale price stabilization by enacting the Market Exchange Law (Shiyifa). Initialized in Kaifeng with a capital endowment of 1 million strings of copper cash from the Inner Treasury and 870,000 strings from regional funds, the state established the Metropolitan Market Exchange Bureau (Shiyiwu), later elevated to a Directorate (Shiyisi) with branches in Hangzhou, Chengdu, Guangzhou, and Chang’an. [7]
Whereas powerful wholesale merchant guilds (hang) and brokerage houses had previously cornered urban markets by buying up provincial merchants’ cargoes at depressed prices and extending high-interest credit, the Market Exchange Bureau allowed small and medium-sized merchants to pledge unsold merchandise, gold, silver, or real estate deeds (diya) as collateral to borrow state funds or purchase state-stockpiled goods on credit. Borrowers paid a statutory interest rate of 10 percent for six months or 20 percent for twelve months—far below the rates charged by private urban pawnshops—with late penalties of 2 percent per month. Together with state-operated pawnshops (Didangsuo) connected to the bureau, the Shiyifa generated hundreds of thousands of strings of annual interest profit for the Song treasury while breaking the credit monopoly of Kaifeng’s great merchant houses. [8]
Mandatory Quotas (Yipei), Sima Guang’s Critique, and the 1086 Repeal
Despite its sophisticated institutional design, the Green Sprouts Act rapidly encountered severe principal-agent distortions across Song China’s more than 1,200 counties. Because the central government in Kaifeng evaluated, promoted, and fined county magistrates based on the volume of Green Sprouts loans disbursed and the punctuality of interest collections, local officials abandoned the principle of voluntary borrowing. Through a coercive practice known as “compulsory apportionment” (yipei), magistrates forced every registered household across all five wealth grades—including prosperous landowners who had no need to borrow and destitute landless laborers with no capacity to repay—to accept fixed seasonal loan quotas.
Even worse, because loans were disbursed and collected in copper cash while peasants sold grain at depressed post-harvest prices to obtain coin, the combination of copper coin scarcity (“money famine,” qianhuang), clerical bribes, and commutation markups frequently pushed the effective burden of a six-month loan from the statutory 20 percent to 40 or 60 percent. During drought years, when mutual-guarantee groups were held jointly liable for neighbors who fled their villages, state runners flogged guarantors and seized their draft oxen and cottages to satisfy granary arrears.
Within the imperial court, the conservative faction led by the eminent historian Sima Guang, alongside scholar-officials Su Shi, Ouyang Xiu, and Han Qi, mounted a relentless critique of the New Policies. In memorials to Emperor Shenzong, Sima Guang argued that private moneylenders, however greedy, could not deploy state torture, prison cells, or tax collectors to extract repayment, whereas the Green Sprouts Law turned county magistrates into ruthless debt collectors who drained the countryside of circulating copper cash. Following the death of Emperor Shenzong in April 1085 and the death of Wang Anshi in May 1086, Empress Dowager Gao appointed Sima Guang as Chief Councillor during the Yuanyou regency. In the third lunar month of 1086, Sima Guang formally abolished the Green Sprouts Law and dismantled the Market Exchange Bureaus—only for Wang Anshi’s reformist partisans to revive a more predatory, purely fiscal version of the loans under Emperor Zhezong and Cai Jing in the 1090s, cementing a bitter factional cleavage that paralyzed the Northern Song state until the Jurchen conquest of Kaifeng in 1127.
Theoretical & Balance-Sheet Transmission Mechanism
In the Kindleberger–Minsky taxonomy of financial instability (Kindleberger, 1978; Minsky, 1986) and Irving Fisher’s (1933) debt-deflation framework, speculative asset booms become systemic crises when credit expansion shifts balance sheets from hedge finance (cash flows covering principal and interest) to speculative and Ponzi finance (relying on rising asset prices and short-term margin roll-overs).
Once monetary tightening or an exogenous shock halts price appreciation, forced margin liquidations trigger Fisherian debt-deflation: fire-sale asset discounts erode bank collateral values, contracting credit supply across the real economy.
Sources and Further Reading
- Richard von Glahn, “ Public Finance (Chapter 9) — The Cambridge Economic History of China,” Cambridge University Press, 2022. Peer-Reviewed / Academic Research
- Ulrich Theobald, “ Qingmiaofa 青苗法 — The Green Sprouts Law,” ChinaKnowledge.de: An Encyclopaedia on Chinese History, Literature and Art, 2016. Historical & Financial Reference
- Ulrich Theobald, “ Shiyifa 市易法 — The Market Exchange Law,” ChinaKnowledge.de: An Encyclopaedia on Chinese History, Literature and Art, 2016. Historical & Financial Reference
- Ulrich Theobald, “ Diandang 典當 and Changshengku 長生庫 — Traditional Chinese Pawnshops,” ChinaKnowledge.de: An Encyclopaedia on Chinese History, Literature and Art, 2016. Historical & Financial Reference
- Charles Hartman, “ Structures of Governance in Song Dynasty China, 960–1279 CE,” Cambridge University Press, 2023. Peer-Reviewed / Academic Research
- Denis Twitchett and Paul Jakov Smith (eds.), “ Song in a Multipolar World — Middle Imperial China, 900–1350,” Cambridge University Press, 2016. Peer-Reviewed / Academic Research
- Irving Fisher — "The Debt-Deflation Theory of Great Depressions," Econometrica 1, no. 4 (FRASER Federal Reserve Archive, 1933): 337–357 Central Bank / Monetary Authority
- Charles P. Kindleberger & Robert Z. Aliber — Manias, Panics, and Crashes: A History of Financial Crises (Palgrave Macmillan) Peer-Reviewed / Academic Research
Cite This Historical Dossier (APA / Chicago)
APA (7th ed.): Ç., S. (Ed.). (2026). The Green Sprouts Act of 1069: Wang Anshi's State Microcredit Experiment in Song China. In Forgotten Fortunes Historical Monograph Series (Forgotten Fortunes Editorial Desk). https://forgottenfortunes.net/green-sprouts-act-wang-anshi-loans/
MLA (9th ed.): Ç., Soner, ed. "The Green Sprouts Act of 1069: Wang Anshi's State Microcredit Experiment in Song China." Forgotten Fortunes: Financial & Monetary History Archive, 2026, https://forgottenfortunes.net/green-sprouts-act-wang-anshi-loans/.
Chicago (17th ed.): Ç., Soner, ed. "The Green Sprouts Act of 1069: Wang Anshi's State Microcredit Experiment in Song China." Forgotten Fortunes Historical Monograph Series (Forgotten Fortunes Editorial Desk), September 16, 2026. https://forgottenfortunes.net/green-sprouts-act-wang-anshi-loans/.
Have an idea for another financial history documentary or article? Request a story →