In This Article
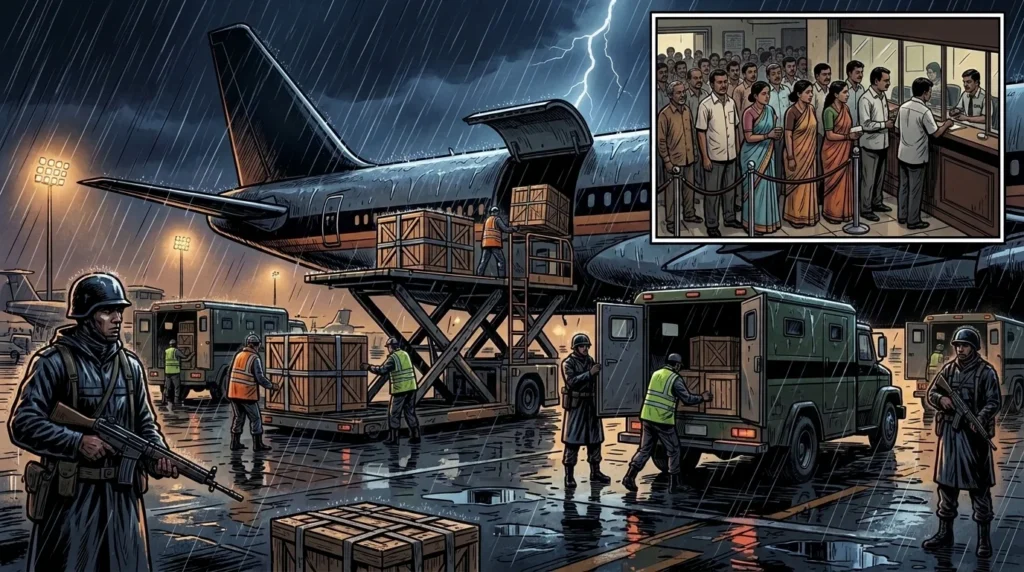
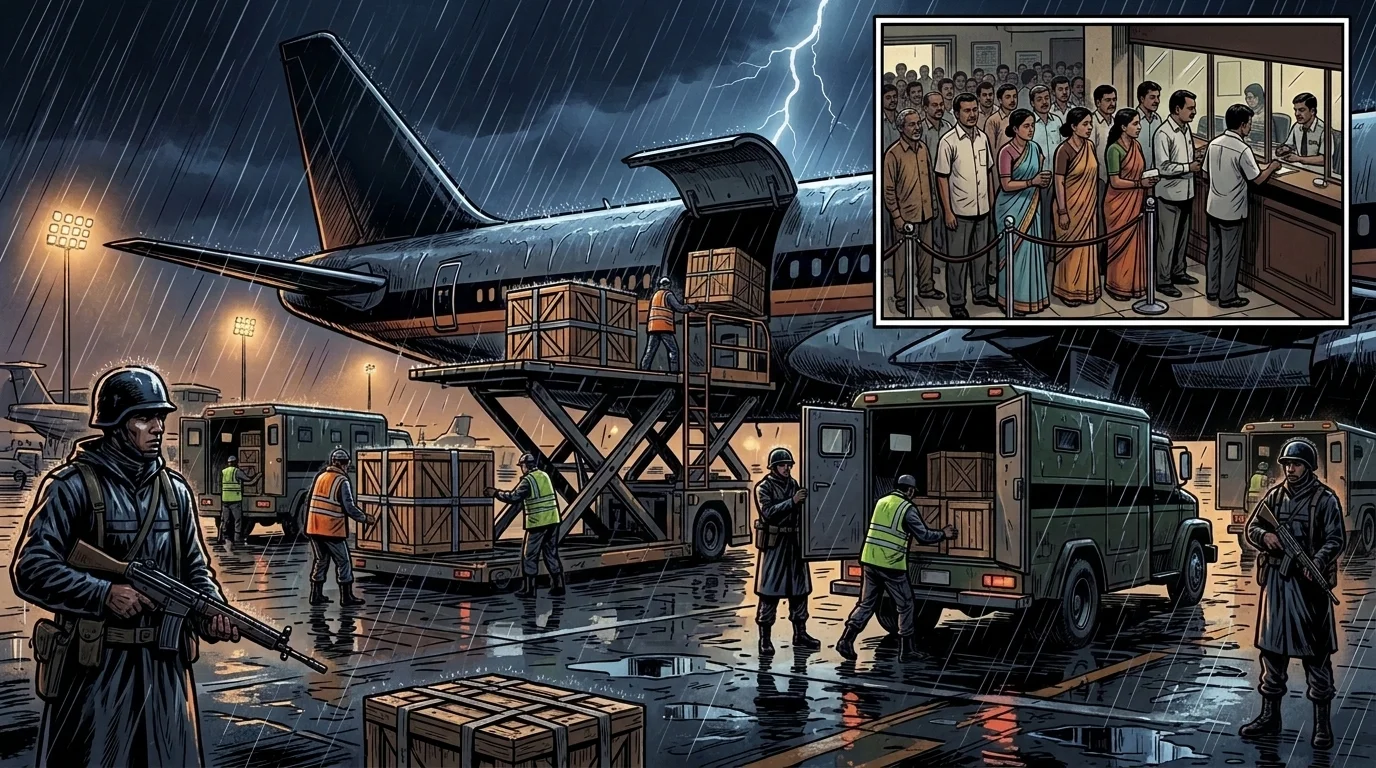
India’s gold airlift reflected the urgency of its 1991 external-payments crisis. Few monetary histories illustrate the tension between external solvency, domestic price stability, and currency administration as starkly as India’s trajectory between 1991 and 2016. In the summer of 1991, after decades of inward-looking import substitution and widening fiscal deficits, India’s usable foreign-exchange reserves plunged to approximately $1.1 billion—barely sufficient to cover two weeks of essential imports. Faced with the immediate prospect of sovereign default on external debt obligations, the Reserve Bank of India (RBI) and the State Bank of India (SBI) executed a covert emergency operation, physically airlifting 67 tonnes of sovereign and confiscated gold to European vaults in Zurich and London to raise $600 million in hard-currency liquidity alongside a two-step devaluation of the Indian rupee of roughly 18% to 19% in July 1991. A quarter-century later, having rebuilt its external buffers to hundreds of billions of dollars, India embarked on two momentous domestic monetary experiments in 2016: the statutory institutionalization of Flexible Inflation Targeting (FIT) under an amended Reserve Bank of India Act, followed on November 8, 2016 by Prime Minister Narendra Modi’s surprise broadcast canceling the legal tender status of all ₹500 and ₹1,000 banknotes—representing 86% of currency in circulation, or ₹15.41 lakh crore—of which 99.3% (₹15.31 lakh crore) ultimately returned to the banking system. [1]
Fiscal Deterioration and the 1990–1991 External Liquidity Crisis
The roots of India’s 1991 balance-of-payments emergency lay in the macroeconomic imbalances built up during the 1980s. Throughout the seventh Five-Year Plan (1985–1990), the consolidated fiscal deficit of the central and state governments climbed above 9% of gross domestic product, financed increasingly through automatic monetization by the RBI via ad hoc Treasury bills and high-cost external commercial borrowings. Under India’s complex web of industrial licensing and quantitative import restrictions—colloquially termed the License Raj—export growth remained sluggish while debt-service ratios steadily deteriorated. [2]
The external trigger arrived in August 1990 when Iraq invaded Kuwait. Crude oil prices doubled on world markets, swelling India’s petroleum import bill from roughly $2.0 billion to $5.7 billion within months, while hundreds of thousands of Indian workers in the Persian Gulf were forced to evacuate, cutting off a vital stream of hard-currency remittances. Simultaneously, political instability in New Delhi—where the minority governments of V. P. Singh and Chandra Shekhar succeeded one another in late 1990 and early 1991—alarmed international credit rating agencies. Moody’s and Standard & Poor’s downgraded India’s sovereign debt to the threshold of non-investment grade, shutting India out of international commercial paper markets and prompting non-resident Indians (NRIs) to withdraw dollar-denominated deposits at an accelerating pace of more than $300 million per month by the spring of 1991. [3]
| Documented Figure / Metric | Historical Significance & Archival Context |
|---|---|
| $600 million | Although leaks to the Indian press ignited fierce parliamentary uproar over the humiliation of pawning national gold, the $600 million combined gold-backed bridge financing prevented a sovereign default and bought critical breathing space, allowing the RBI to redeem and repurchase all pledged gold by November 1991. |
| ₹21.2 | Rangarajan—devaluing the currency by a cumulative 18% to 19% against major international currencies (raising the dollar exchange rate from roughly ₹21.2 to ₹25.8). |
| $350 billion | Over the two decades following the 1991 crisis, India's external vulnerability receded as foreign-exchange reserves expanded past $350 billion, yet domestic monetary management struggled with persistent inflationary pressures. |
| ₹17.77 lakh crore | On the eve of November 8, 2016, India's total currency in circulation stood at approximately ₹17.77 lakh crore ($266 billion), of which ₹500 and ₹1,000 denominations accounted for 86.4% by value—totalling ₹15.41 lakh crore (roughly 1,541,790 crore rupees across more than 24 billion individual pieces of paper currency). |
Pledging the Family Jewels: The 67-Tonne Gold Airlift and July 1991 Devaluation
By May and June 1991, Governor S. Venkitaramanan at the Reserve Bank of India and senior officials in the Ministry of Finance confronted an arithmetic impossibility: short-term external credit lines were refusing rollovers, and liquid foreign currency reserves had dropped to $1.1 billion. To prevent a technical default before an International Monetary Fund (IMF) stabilization program could be negotiated by an incoming government, Indian authorities turned to the nation’s bullion holdings. [4]
In late May 1991, the State Bank of India leased approximately 20 tonnes of gold that had been confiscated from smugglers by customs authorities over preceding decades and held in the government’s mint vaults. The 20 tonnes were flown out of Bombay (now Mumbai) to the Union Bank of Switzerland (UBS) in Zurich under a sale-and-repurchase agreement that raised approximately $200 million in immediate foreign exchange. Because this gold came from government non-monetary stocks rather than the RBI’s statutory currency reserve, it bypassed the strict statutory ceiling of the Reserve Bank of India Act, 1934, which permitted the central bank to hold no more than 15% of its official monetary gold outside India. [5]
The relief proved fleeting. In June 1991, as P. V. Narasimha Rao assumed office as Prime Minister and appointed former RBI Governor Dr. Manmohan Singh as Finance Minister, the RBI took the extraordinary step of invoking its statutory leeway to ship monetary gold abroad. In four tightly guarded consignments between July 4 and July 18, 1991—memorable for a minor tire mishap on an armored bullion van traveling from the RBI building on Mint Road to Sahar International Airport—the central bank airlifted 46.91 tonnes (roughly 47 tonnes) of its official gold reserves to the vaults of the Bank of England in London, holding it as physical collateral against short-term credit tranches totaling $405 million provided by the Bank of England and the Bank of Japan. Although leaks to the Indian press ignited fierce parliamentary uproar over the humiliation of pawning national gold, the $600 million combined gold-backed bridge financing prevented a sovereign default and bought critical breathing space, allowing the RBI to redeem and repurchase all pledged gold by November 1991. [6]
Simultaneously, on July 1 and July 3, 1991, the RBI executed a two-stage downward adjustment of the rupee—code-named in internal communications between Manmohan Singh and RBI Deputy Governor C. Rangarajan—devaluing the currency by a cumulative 18% to 19% against major international currencies (raising the dollar exchange rate from roughly ₹21.2 to ₹25.8). This sharp exchange-rate correction was paired within weeks with the landmark July 24, 1991 Industrial Policy Statement and union budget, dismantling industrial licensing for most sectors, slashing peak import tariffs, transitioning the rupee toward current-account convertibility by 1993–1994, and phasing out automatic deficit monetization through the historic 1994 and 1997 agreements abolishing ad hoc Treasury bills. [7]
The 2016 Statutory Shift to Flexible Inflation Targeting
Over the two decades following the 1991 crisis, India’s external vulnerability receded as foreign-exchange reserves expanded past $350 billion, yet domestic monetary management struggled with persistent inflationary pressures. Beginning in 1998, the RBI had replaced monetary-aggregate targeting with a “multiple indicator approach” that weighed credit growth, output gaps, exchange rates, and wholesale prices simultaneously. Following the 2008 global financial crisis, however, a combination of fiscal stimulus, rural wage adjustments, and food supply bottlenecks pushed Indian consumer price inflation into double digits between 2009 and 2013, eroding household purchasing power, encouraging household gold imports, and destabilizing the rupee during the 2013 “taper tantrum.” [8]
In September 2013, newly appointed RBI Governor Raghuram Rajan commissioned an expert committee chaired by Deputy Governor Urjit Patel to modernize India’s monetary policy architecture. Reporting in January 2014, the Urjit Patel Committee recommended replacing the multiple-indicator framework with a clear nominal anchor based on headline Consumer Price Index (CPI) inflation. This recommendation culminated in the Monetary Policy Framework Agreement of February 2015 and the statutory amendment of the Reserve Bank of India Act, 1934 via the Finance Act in May 2016.
Under the amended statutory regime, India formally adopted Flexible Inflation Targeting (FIT). The central government, in consultation with the RBI, set a headline CPI inflation target of 4.0% with a symmetrical tolerance band of plus or minus 2 percentage points (establishing an operational floor of 2.0% and an upper ceiling of 6.0%). If headline inflation breached the 2%–6% band for three consecutive quarters, the RBI became legally obligated to submit a formal report to the government explaining the causes of the failure and the remedial actions proposed. Furthermore, rate-setting authority was transferred from the sole discretion of the RBI Governor to a six-member Monetary Policy Committee (MPC)—comprising three internal RBI officials and three external economists appointed by the government—which convened for its inaugural policy decision in October 2016.
8:00 PM on November 8, 2016: The Demonetization Shock
Barely five months after enshrining rules-based inflation targeting, India’s monetary system experienced the most abrupt physical currency intervention in its post-independence history. At 8:00 PM Indian Standard Time on November 8, 2016, following a tightly compartmented cabinet meeting held earlier that evening, Prime Minister Narendra Modi addressed the nation on live television to announce that effective at midnight—just four hours later—all existing ₹500 and ₹1,000 banknotes (designated in official notifications as Specified Bank Notes, or SBNs) would cease to be legal tender for routine transactions.
The scale of the demonetization was unprecedented for a booming peacetime economy. On the eve of November 8, 2016, India’s total currency in circulation stood at approximately ₹17.77 lakh crore ($266 billion), of which ₹500 and ₹1,000 denominations accounted for 86.4% by value—totalling ₹15.41 lakh crore (roughly 1,541,790 crore rupees across more than 24 billion individual pieces of paper currency). In his broadcast, the Prime Minister framed the measure as a decisive strike against unaccounted wealth (“black money”), tax evasion, counterfeit currency networks, and cash-funded terrorism, while promoting a transition toward formal banking and digital payments. Citizens were granted a 50-day window until December 30, 2016 to deposit their invalidated banknotes into commercial or cooperative bank accounts, or to exchange limited sums over the counter subject to strict daily and weekly withdrawal caps while the RBI’s printing presses raced to print newly redesigned ₹500 and ₹2,000 notes.
Liquidity Squeeze, Economic Disruption, and the 99.3% Return
Because the new ₹2,000 and ₹500 notes had been redesigned with smaller physical dimensions to preserve pre-announcement secrecy, more than 200,000 automated teller machines (ATMs) across India required manual hardware recalibration before they could dispense the new bills. Throughout November and December 2016, severe cash shortages gripped urban and rural markets alike. In an economy where over 80% of employment was informal and more than 90% of consumer transactions were settled in physical currency, the sudden evaporation of cash disrupted agricultural wholesale markets (*mandis*), small-scale manufacturing, construction day-labor, and retail commerce. Empirical cross-district analyses later estimated that the cash contraction reduced economic activity and night-time light intensity in cash-dependent districts by roughly 2 to 3 percentage points during the fourth quarter of 2016, before gradually normalizing as remonetization progressed in mid-2017.
Within the banking system, the demonetization inverted the RBI’s liquidity management problem overnight. Commercial banks were flooded with trillions of rupees in low-cost current and savings account (CASA) deposits, pushing the banking system into massive structural liquidity surplus. To absorb this excess liquidity and prevent a collapse in overnight money-market interest rates, the RBI briefly imposed a 100% incremental Cash Reserve Ratio (CRR) on late-November deposit inflows before deploying large-scale reverse repo operations and Market Stabilization Scheme (MSS) bonds.
Proponents of demonetization had initially hypothesized that between ₹3 lakh crore and ₹5 lakh crore of illicit cash hoards would be destroyed by holders fearful of tax prosecution, potentially yielding a massive fiscal windfall via extinguished central bank liabilities. However, after nearly two years of high-speed optical verification and counting of returned bundles, the Reserve Bank of India published the definitive accounting in its Annual Report on August 29, 2018: out of the ₹15.41 lakh crore of ₹500 and ₹1,000 notes in circulation on November 8, 2016, exactly ₹15.31 lakh crore (99.3%) had been validly returned and credited to the banking system, leaving only ₹10,720 crore (0.7%) unreturned. While the intervention failed to extinguish illicit cash hoards directly, it accelerated the expansion of India’s income-tax filing base, channeled household savings into mutual funds and formal bank deposits, and catalyzed the rapid nationwide adoption of the Unified Payments Interface (UPI), which had been launched earlier in 2016 and transformed India’s retail payments landscape over the ensuing decade.
Theoretical & Balance-Sheet Transmission Mechanism
In the Kindleberger–Minsky taxonomy of financial instability (Kindleberger, 1978; Minsky, 1986) and Irving Fisher’s (1933) debt-deflation framework, speculative asset booms become systemic crises when credit expansion shifts balance sheets from hedge finance (cash flows covering principal and interest) to speculative and Ponzi finance (relying on rising asset prices and short-term margin roll-overs).
Once monetary tightening or an exogenous shock halts price appreciation, forced margin liquidations trigger Fisherian debt-deflation: fire-sale asset discounts erode bank collateral values, contracting credit supply across the real economy.
Sources and Further Reading
- Valerie Cerra and Sweta Chaman Saxena, “ What Caused the 1991 Currency Crisis in India?“, IMF Staff Papers, 2002. International Financial Institution
- Valerie Cerra and Sweta Chaman Saxena, “ What Caused the 1991 Currency Crisis in India? (IMF Working Paper No. 00/29)“, International Monetary Fund, 2000. International Financial Institution
- Philip R. Lane and Sergio L. Schmukler, “ The International Financial Integration of China and India“, World Bank, 2007. International Financial Institution
- Gabriel Chodorow-Reich, Gita Gopinath, Prachi Mishra, and Abhinav Narayanan, “ Cash and the Economy: Evidence from India's Demonetization (NBER Working Paper No. 25370)“, National Bureau of Economic Research, 2018. Peer-Reviewed / Academic Research
- Ashima Goyal, “ Flexible Inflation Targeting: Concepts and Application in India“, Indian Public Policy Review, 2022. Peer-Reviewed / Academic Research
- Ritam Chaurey, Ryan Kim, and Pravin Krishna, “ Liquidity Shocks and Firm Exports: Evidence from Cash Shortages During India's Demonetization“, National Bureau of Economic Research, 2024. Peer-Reviewed / Academic Research
- Irving Fisher — "The Debt-Deflation Theory of Great Depressions," Econometrica 1, no. 4 (FRASER Federal Reserve Archive, 1933): 337–357 Central Bank / Monetary Authority
- Charles P. Kindleberger & Robert Z. Aliber — Manias, Panics, and Crashes: A History of Financial Crises (Palgrave Macmillan) Peer-Reviewed / Academic Research
Cite This Historical Dossier (APA / Chicago)
APA (7th ed.): Ç., S. (Ed.). (2026). India's 1991 Gold Airlift, Flexible Inflation Targeting, and the 2016 Demonetization. In Forgotten Fortunes Historical Monograph Series (Forgotten Fortunes Editorial Desk). https://forgottenfortunes.net/india-1991-gold-airlift-2016-demonetization/
MLA (9th ed.): Ç., Soner, ed. "India's 1991 Gold Airlift, Flexible Inflation Targeting, and the 2016 Demonetization." Forgotten Fortunes: Financial & Monetary History Archive, 2026, https://forgottenfortunes.net/india-1991-gold-airlift-2016-demonetization/.
Chicago (17th ed.): Ç., Soner, ed. "India's 1991 Gold Airlift, Flexible Inflation Targeting, and the 2016 Demonetization." Forgotten Fortunes Historical Monograph Series (Forgotten Fortunes Editorial Desk), September 6, 2026. https://forgottenfortunes.net/india-1991-gold-airlift-2016-demonetization/.
Have an idea for another financial history documentary or article? Request a story →