In This Article
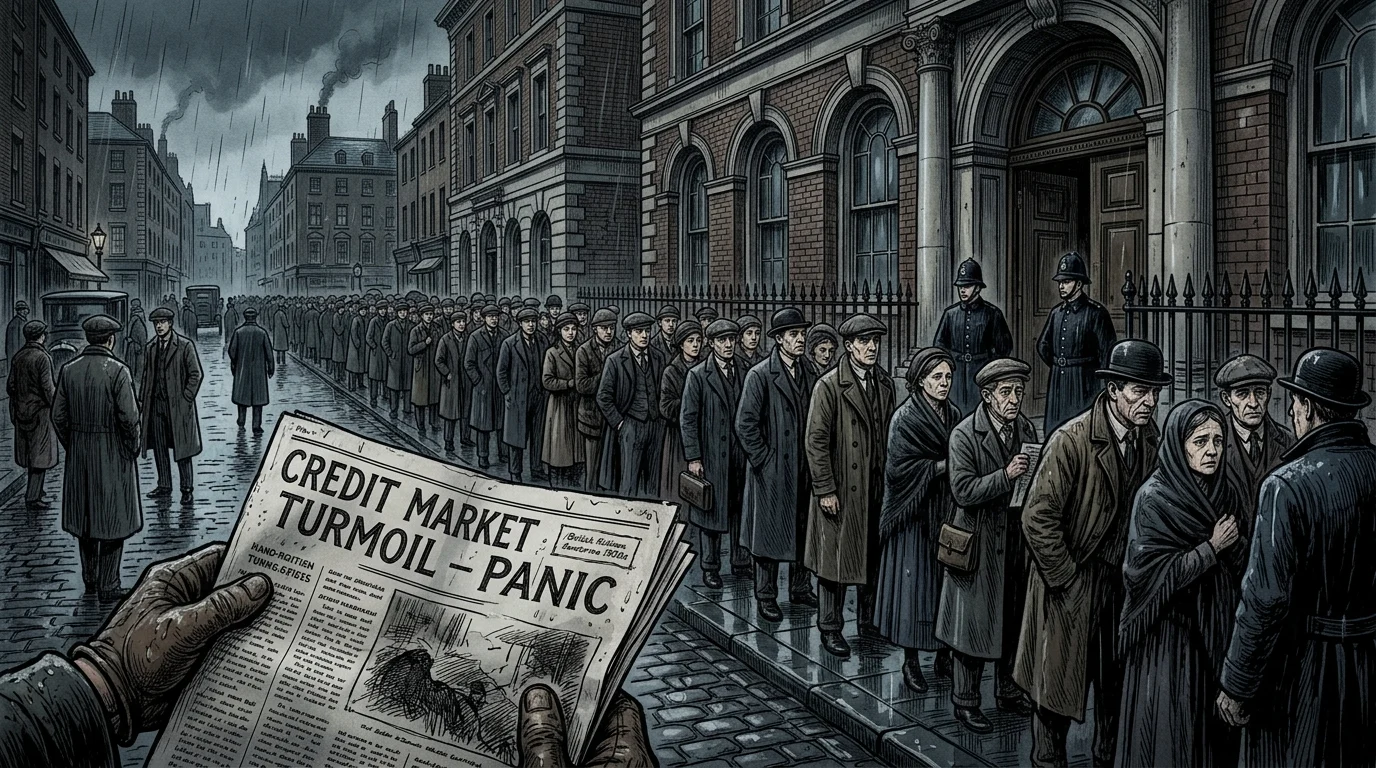
On the evening of September 13, 2007, the BBC reported that Northern Rock—one of the United Kingdom’s largest residential mortgage lenders—had requested emergency liquidity support from the Bank of England [7]. The following morning, after HM Treasury, the Bank of England, and the Financial Services Authority (FSA) formally announced the support facility, nervous savers formed long queues outside Northern Rock branches across the country to pull out their money [1][7]. Within days, retail depositors withdrew £4.6 billion in Britain’s first classic high-street bank run since the collapse of Overend, Gurney and Company in 1866 [4][7].

While television images of anxious customers lining British pavements came to symbolize the onset of the 2007–2008 global financial crisis, economists and financial historians subsequently demonstrated that the street-level panic was the culmination rather than the primary cause of Northern Rock’s collapse [3]. Over the preceding decade, the former building society had expanded its balance sheet more than sixfold by funding long-term residential mortgages with short-term debt raised in domestic and international wholesale money markets [3][4]. When global credit markets seized up in August 2007, institutional lenders quietly stopped rolling over Northern Rock’s short-term liabilities—a silent wholesale run that crippled the bank weeks before retail savers queued at its doors [3][4].
Demutualisation and the Shift from Retail Savings (1997–2006)
For well over a century prior to the 1990s, Northern Rock operated in North East England as a mutual building society owned by its member savers and borrowers. Under the traditional building society model, residential home loans were funded predominantly through stable retail customer deposits gathered across a regional branch network. Amid a wave of British building society conversions during the late 1980s and 1990s, Northern Rock demutualised on October 1, 1997, converting into a public limited company (Northern Rock plc) listed on the London Stock Exchange [5]. Its conversion distributed shares to hundreds of thousands of former members, creating a broad base of roughly 150,000 small private shareholders alongside institutional investors [6].
Freed from the statutory lending and funding constraints that governed mutual societies, Northern Rock embarked on a rapid national expansion. Between June 1998 and June 2007, the bank’s total assets grew from £17.4 billion to £113.5 billion [3]. Its traditional retail deposit base did not keep pace with this aggressive asset growth, rising much more modestly from £10.4 billion to £24.0 billion over the same nine-year span [3][4]. Rather than constraining its mortgage origination to match retail deposit inflows, management turned to global capital markets and short-term wholesale borrowing to finance the remainder of its balance sheet [3][4].
To capture market share across the UK housing market, Northern Rock competed aggressively on loan terms and volume. Among its riskiest offerings were high-leverage mortgage products that allowed borrowers to take out loans worth up to 125 percent of a property’s appraised value—loans that carried substantially higher default rates when housing prices stalled [2]. By mid-2007, retail savings accounted for less than a quarter of the bank’s total funding, leaving its day-to-day operations dependent on continuous access to liquid capital markets [3][4].
| Documented Figure / Metric | Historical Significance & Archival Context |
|---|---|
| 30 percent | Northern Rock's share price plunged by 30 percent, and thousands of retail depositors queued outside branches or tried to log into overburdened online banking systems to withdraw their savings. |
| £2,000 | At the time, the UK's Financial Services Compensation Scheme fully protected only the first £2,000 of a saver's deposit and 90 percent of the next £33,000—creating a strong incentive for depositors with larger balances, or those fearing administrative delays in a receivership, to withdraw their money immediately. |
| £55 billion | By that point, total state support in loans and guarantees had reached roughly £55 billion, and in August 2008 HM Treasury directly assumed £14.5 billion in remaining emergency loans from the Bank of England. |
The Wholesale Funding Mechanism and Balance-Sheet Vulnerability
Northern Rock’s funding architecture relied on two main non-retail channels: residential mortgage-backed securities (RMBS) and short-term wholesale money market borrowing [3][4]. Through its off-balance-sheet securitisation vehicles, the bank pooled residential mortgages and sold repackaged debt securities to international institutional investors, while also issuing covered bonds and borrowing directly from interbank and wholesale lenders [3][4]. This originate-and-fund model enabled Northern Rock to recycle capital rapidly and expand mortgage lending far beyond the capacity of its branch network [4].
In a seminal 2009 study of the collapse, economist Hyun Song Shin showed that Northern Rock’s fatal vulnerability stemmed less from securitisation per se than from extreme balance-sheet leverage combined with heavy reliance on short-term institutional funding [3]. By borrowing at short maturities from money market funds and institutional counterparties to finance illiquid, multi-decade residential mortgages, the bank created a severe maturity mismatch [3][4]. So long as global credit remained abundant and measured market volatility stayed low, institutional creditors willingly rolled over these short-term obligations [3].
Meanwhile, the United Kingdom’s supervisory framework was poorly equipped to address systemic liquidity risks. Under reforms introduced in 1997, banking oversight was divided among the Tripartite Authorities: the Financial Services Authority supervised individual institutions, the Bank of England oversaw overall monetary and financial stability, and HM Treasury held responsibility for public finances and statutory intervention [1][2]. Standard regulatory metrics of the era focused heavily on risk-weighted capital adequacy ratios—which appeared healthy on Northern Rock’s books because residential mortgages carried low risk weights—rather than on maturity mismatch or wholesale funding liquidity [3]. Furthermore, although the Tripartite Authorities had identified gaps in their legal and operational capability to resolve a failing bank during a 2004 review, addressing those deficiencies was not treated as an urgent policy priority during years of benign economic growth [2].
The August 2007 Credit Freeze and the September Bank Run
The fragility of Northern Rock’s funding model was exposed in August 2007, when mounting losses in the United States subprime mortgage market triggered a sudden repricing of credit risk across North American and European money markets [3][4]. As global banks and institutional investors hoarded liquidity and shrank their balance sheets, appetite for mortgage-backed paper and short-term bank debt evaporated [3]. Northern Rock saw its credit default swap spreads widen sharply and its share price slide as institutional lenders refused to roll over maturing short-term funding [3][4].
Unable to replace its wholesale liabilities in frozen private markets, Northern Rock informed the FSA and the Bank of England that it faced a critical liquidity shortfall [4]. Behind closed doors, the Tripartite Authorities debated how to provide emergency central bank support. Mervyn King, then Governor of the Bank of England, later stated that he had advised keeping the emergency lending facility confidential to prevent public panic, whereas the FSA and legal advisers concluded that market disclosure rules required a public announcement [7]. Before the official statement could be issued on the morning of September 14, BBC business editor Robert Peston broke the news on the evening of September 13 that Northern Rock had sought emergency assistance from the Bank of England [7].
On September 14, 2007, HM Treasury, the Bank of England, and the FSA released a joint statement confirming that the Chancellor of the Exchequer had authorized the central bank to provide a liquidity support facility to Northern Rock against appropriate collateral and at a penalty interest rate premium [1][4]. Although regulators emphasized that the FSA judged Northern Rock to be solvent and that the facility was intended strictly to bridge temporary market turbulence, the revelation had the opposite effect on public confidence [1][7]. Northern Rock’s share price plunged by 30 percent, and thousands of retail depositors queued outside branches or tried to log into overburdened online banking systems to withdraw their savings [7].
Sovereign Guarantees and Emergency Liquidity
The retail run compounded Northern Rock’s wholesale funding freeze. Within days of the September 14 announcement, retail depositors pulled £4.6 billion from the bank, forcing Northern Rock to draw immediately and heavily on the Bank of England’s emergency facility [4]. At the time, the UK’s Financial Services Compensation Scheme fully protected only the first £2,000 of a saver’s deposit and 90 percent of the next £33,000—creating a strong incentive for depositors with larger balances, or those fearing administrative delays in a receivership, to withdraw their money immediately.
To halt the run and prevent contagion from spreading to other British mortgage lenders, Chancellor of the Exchequer Alistair Darling intervened on September 17, 2007, announcing that HM Treasury would guarantee all existing deposits at Northern Rock. Subsequent Treasury guarantee arrangements were extended to cover retail depositors and wholesale creditors alike [2][4]. The sovereign guarantee succeeded in stopping the retail queues and stemming the immediate threat of systemic instability, though Northern Rock remained completely dependent on state liquidity [2][4]. By the end of December 2007, the bank’s outstanding emergency borrowing from the Bank of England stood at £28.5 billion [4].
A subsequent investigation by the National Audit Office (NAO) concluded that while the Treasury had successfully protected depositors and halted the panic, its early oversight of the supported bank showed strain [2]. Even as a condition of state support required Northern Rock to curb its overall lending, the company continued writing high-risk mortgages at up to 125 percent loan-to-value under existing commercial pipelines—exposing taxpayers to elevated credit risk as the British housing market began to turn downward [2].
Nationalisation, Shareholder Disputes, and Regulatory Legacy
Throughout late 2007 and early 2008, HM Treasury evaluated long-term resolution options for Northern Rock, weighing two remaining private-sector rescue proposals—one led by Richard Branson’s Virgin consortium and another by the bank’s existing management—against taking the bank into public ownership [2]. Concluding that neither private bid offered sufficient financial backing, resilience, or value for money to safeguard taxpayers, the government announced in February 2008 that Northern Rock would be nationalised [2][4]. Under the Banking (Special Provisions) Act 2008, the company’s shares were transferred into temporary public ownership on February 22, 2008 [5]. By that point, total state support in loans and guarantees had reached roughly £55 billion, and in August 2008 HM Treasury directly assumed £14.5 billion in remaining emergency loans from the Bank of England [4][6].
The nationalisation wiped out Northern Rock’s equity holders, including around 150,000 small retail shareholders—many of them former building society members and staff—as well as hedge funds SRM Global and RAB Capital, which had accumulated large stakes during the crisis [6]. Under the statutory valuation framework, independent valuer BDO was required to assess the company’s value on the assumption that all state financial support had been withdrawn and that Northern Rock was no longer a going concern [6][7]. In March 2010, BDO determined that the shares had zero residual value at the moment of takeover [6]. Shareholders challenged the uncompensated expropriation in the UK High Court and Court of Appeal before taking their case to the European Court of Human Rights, which on August 1, 2012, unanimously rejected the claim as inadmissible, ruling that the UK government had acted legitimately to prevent moral hazard and protect the wider national economy [6][7].
Under state ownership, Northern Rock was restructured on January 1, 2010, into two separate entities: a “good bank” (Northern Rock plc) holding retail deposits and performing mortgages, and a “bad bank” (Northern Rock Asset Management plc, later folded into UK Asset Resolution alongside Bradford & Bingley) tasked with winding down the legacy loan book [4][5]. On January 1, 2012, the government completed the sale of Northern Rock plc to Virgin Money for £747 million [4][5]. By 2016, as legacy assets were gradually recovered, the National Audit Office estimated a nominal net gain of £5 billion to the government from the intervention (though not on a net present value basis) [4]. Beyond the balance sheet, the trauma of Northern Rock’s collapse prompted the Bank of England to provide £61.2 billion in covert emergency liquidity to Royal Bank of Scotland and HBOS in 2008, led to the dismantling of the Tripartite system, and drove international regulatory reforms under Basel III that introduced strict liquidity coverage ratios alongside traditional capital requirements [3][7].
Theoretical & Balance-Sheet Transmission Mechanism
In the Kindleberger–Minsky taxonomy of financial instability (Kindleberger, 1978; Minsky, 1986) and Irving Fisher’s (1933) debt-deflation framework, speculative asset booms become systemic crises when credit expansion shifts balance sheets from hedge finance (cash flows covering principal and interest) to speculative and Ponzi finance (relying on rising asset prices and short-term margin roll-overs).
Once monetary tightening or an exogenous shock halts price appreciation, forced margin liquidations trigger Fisherian debt-deflation: fire-sale asset discounts erode bank collateral values, contracting credit supply across the real economy.
Sources and Further Reading
- HM Treasury, Bank of England, and Financial Services Authority, “ Liquidity Support Facility for Northern Rock plc,” Bank of England, 2007-09-14. Central Bank / Monetary Authority
- National Audit Office, “ HM Treasury: The nationalisation of Northern Rock,” National Audit Office, 2009-03-20. Historical & Financial Reference
- Hyun Song Shin, “ Reflections on Northern Rock: The Bank Run That Heralded the Global Financial Crisis,” American Economic Association (Journal of Economic Perspectives), 2009. Peer-Reviewed / Academic Research
- Bailey Decker, Jack French, and Eming Shyu, “ United Kingdom: Northern Rock Emergency Liquidity Program, 2007,” Yale Program on Financial Stability (Journal of Financial Crises), 2025. Peer-Reviewed / Academic Research
- Building Societies Association, “ List of demutualised building societies,” Building Societies Association. Historical & Financial Reference
- Jill Treanor, “ Northern Rock compensation claim rejected,” The Guardian, 2012-08-01. Historical & Financial Reference
- BBC News, “ Northern Rock’s Bank of England bailout ‘should have been secret’,” BBC News, 2017-09-12. Central Bank / Monetary Authority
- Irving Fisher — "The Debt-Deflation Theory of Great Depressions," Econometrica 1, no. 4 (FRASER Federal Reserve Archive, 1933): 337–357 Central Bank / Monetary Authority
- Charles P. Kindleberger & Robert Z. Aliber — Manias, Panics, and Crashes: A History of Financial Crises (Palgrave Macmillan) Peer-Reviewed / Academic Research
Cite This Historical Dossier (APA / Chicago)
APA (7th ed.): Ç., S. (Ed.). (2026). Northern Rock and the 2007 UK Bank Run: Wholesale Funding and Crisis. In Forgotten Fortunes Historical Monograph Series (Forgotten Fortunes Editorial Desk). https://forgottenfortunes.net/northern-rock-bank-run-uk-financial-history/
MLA (9th ed.): Ç., Soner, ed. "Northern Rock and the 2007 UK Bank Run: Wholesale Funding and Crisis." Forgotten Fortunes: Financial & Monetary History Archive, 2026, https://forgottenfortunes.net/northern-rock-bank-run-uk-financial-history/.
Chicago (17th ed.): Ç., Soner, ed. "Northern Rock and the 2007 UK Bank Run: Wholesale Funding and Crisis." Forgotten Fortunes Historical Monograph Series (Forgotten Fortunes Editorial Desk), August 28, 2026. https://forgottenfortunes.net/northern-rock-bank-run-uk-financial-history/.
Have an idea for another financial history documentary or article? Request a story →