In This Article
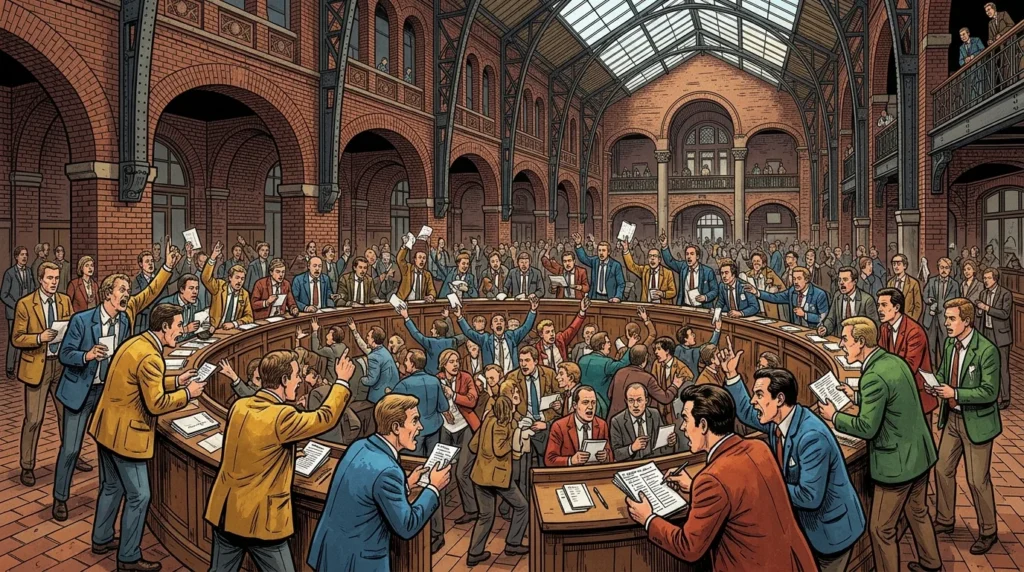
During the first half of the seventeenth century, while recurrent harvest failures,Thirty Years’ War requisitions, and debased silver coinages triggered subsistence crises across much of continental Europe, the Dutch Republic achieved an unprecedented degree of price stability and commercial liquidity. That resilience rested on three interlocking institutional pillars in Amsterdam: the Baltic bulk grain trade known to contemporaries as the Moedernegotie (“Mother of All Trades”) centered on the Damrak Korenbeurs, the weekly publication of standardized commodity price currents (Prijscouranten) beginning in 1585, and the ledger-money clearing system of the Amsterdamsche Wisselbank founded in 1609. Yet the same commercial infrastructure, surplus capital, and legal tolerance for forward contracting that stabilized bread prices also incubated Europe’s most famous speculative derivatives frenzy: the winter 1636–1637 Tulpenmanie (Tulip Mania), in which tavern-based forward contracts (windhandel) surged and collapsed as self-governing floral guilds and the States of Holland converted binding futures into low-fee option contracts. [1]

The Moedernegotie and the Korenbeurs as Europe’s Granary
Because the low-lying, waterlogged peat soils of Holland and Friesland were ill-suited to large-scale cereal cultivation, the Dutch provinces shifted their rural economy toward high-value dairy farming, industrial hemp, madder dye, and horticultural crops while relying on maritime imports for basic caloric survival. Following the 1581 Act of Abjuration and the fall of Antwerp to Spanish forces in 1585, Amsterdam consolidated control over the Baltic grain trade—universalized in Dutch political economy as the Moedernegotie. Every spring and autumn, fleets of 700 to 800 Dutch ships sailed through the Danish Sound to Baltic ports led by Danzig (Gdańsk), Königsberg, Riga, and Elbing to load tens of thousands of lasten (one Amsterdam last equaling roughly 3,000 liters or two metric tons) of Polish and Prussian rye and wheat. [2]
The decisive cost advantage of Dutch merchants lay in the fluyt, a pear-shaped, flat-bottomed cargo vessel perfected in Hoorn around 1595. Stripped of heavy naval artillery and rigged with simplified pulley tackle, a three-masted fluyt of 200 to 300 tons could be sailed by a crew of nine to twelve mariners—roughly half the manning requirement of rival English or Hanseatic vessels. Freight charges between Danzig and Amsterdam fell so low that Polish estate grain could be landed on the Amstel cheaper than overland grain hauled fifty miles inside France or Germany. [3]
To prevent speculative hoarding from starving the domestic market while still profiting from continental shortages, Amsterdam constructed a vast physical buffer stock. Multi-story brick warehouses (pakhuizen) lining the Oudezijds and Nieuwezijds canals, Brouwersgracht, and Prinseneiland held up to 100,000 lasten of grain—enough to feed the urban population of Holland for more than a year while leaving a substantial exportable surplus. In 1616–1617, municipal architect Hendrick de Keyser erected a dedicated wooden Korenbeurs (Grain Exchange) on pilings over the Damrak water. Along its open-air colonnaded galleries, merchants inspected numbered wooden sample boxes of Danzig rye, Prussian wheat, and Livonian barley, while sworn municipal grain measurers (korenmeters) and setters (korenzetters) enforced uniform volumetric measures. Whenever Mediterranean or Western European harvests failed—as occurred in Italy during the 1590s and across Germany and France in 1622–1623 and 1630–1631—Amsterdam merchants released stored Baltic rye at high arbitrage margins, smoothing domestic Dutch bread prices via municipal broodzetting (bread weight-and-price schedules) while draining gold and silver specie from famine-stricken neighbors. [4]
Information Arbitrage: The Weekly Prijscouranten
Efficient spatial arbitrage between the Baltic, the North Sea, and the Mediterranean required verifiable, high-frequency price discovery. After Hendrick de Keyser’s central Commodity Exchange (Koopmansbeurs) opened on the Rokin in 1611, over four hundred sworn brokers (makelaars) gathered daily between noon and two o’clock around forty-six numbered stone pillars to quote spot and forward prices for grain, herring, Baltic timber, Asian spices, colonial sugar, marine insurance, and bills of exchange. [5]
Beginning in 1585—and institutionalized under municipal regulation in 1613—sworn broker committees compiled and printed weekly single-sheet price lists known as Cours van de Koopmanschappen tot Amsterdam (Prijscouranten). Distributed by postal couriers to counting houses in Danzig, Hamburg, London, Venice, Seville, and Livorno, the Prijscouranten listed wholesale price ranges for more than two hundred standardized commodities alongside foreign exchange rates on major European fairs. By publishing transparent benchmark prices in a single reference currency, Amsterdam compressed bid-ask spreads across northern Europe and enabled merchants to lock in forward grain and freight contracts months before the spring thaw opened the Baltic ports. [6]
The 1609 Wisselbank and the Stability of the Bankgeld Agio
Commodity price transparency could not function without a stable monetary unit of account. At the turn of the seventeenth century, Dutch circulation was flooded with between 800 and 1,000 distinct gold and silver coins minted by seven provincial estates, dozens of imperial cities, and foreign sovereigns. In this competitive environment, Gresham’s Law operated relentlessly: moneychangers (kassiers) culled full-weight heavy silver coins to melt or export, leaving worn, clipped, and debased coins in domestic circulation and driving the market price of silver guilders down by 8 to 10 percent over the decade prior to 1609. [7]
To halt this monetary erosion, the Amsterdam city council founded the Amsterdamsche Wisselbank (Bank of Amsterdam) on January 31, 1609, housed inside the ground floor of the Town Hall on Dam Square. The municipal ordinance required that all bills of exchange negotiated in Amsterdam with a value of 600 guilders or more be settled exclusively through book-entry transfers on the ledgers of the Wisselbank. Merchants deposited heterogeneous foreign and domestic coins or raw bullion at the bank’s assay office, which credited their accounts in standardized “bank guilders” (gulden banco or bankgeld) fixed strictly to the intrinsic fine-silver weight of the republic’s legal-tender rijksdaalder (containing 25.40 grams of fine silver, valued at 2.5 guilders). [8]
Because bankgeld was backed 100 percent by vaulted precious metal, immune to municipal seizure, and transferable without counting fees, it traded at a consistent market premium—the agio—of 4 to 5 percent above circulating pocket coins (courantgeld). Throughout the hyperinflationary Kipper- und Wipperzeit (1619–1623) that ravaged the Holy Roman Empire, Amsterdam’s wholesale prices denominated in bankgeld remained rock-solid, anchoring international grain and freight contracts across Europe.
Collegia Taverns and the Mechanics of Tulip Windhandel
While the Korenbeurs, Koopmansbeurs, and Wisselbank governed wholesale merchant capital, Amsterdam’s legal framework also shaped how non-institutional traders speculated in forward contracts. Under repeated ordinances enacted by the States General starting in February 1610—originally passed to curb naked short-selling of Dutch East India Company (VOC) shares by Isaac Le Maire’s bear syndicate—time contracts in which the seller did not physically possess the underlying asset at the moment of sale were declared legally unenforceable in provincial courts as wagers (windhandel, literally “trading in the wind”).
This legal vacuum played a decisive role when exotic tulip bulbs, first imported from the Ottoman Empire via Vienna and cultivated by botanist Carolus Clusius at Leiden in 1593, became the object of intense commercial speculation in the mid-1630s. The most coveted tulips were “broken” varieties (rosen, violetten, and bizarden) whose petals displayed vivid flame-like streaks caused by a mosaic potyvirus transmitted by peach aphids. Because broken tulips could not be bred true from seed—propagating only through one or two slow-growing vegetative offsets (klisters) per mother bulb each year—supply was rigidly inelastic.
Normally, tulip bulbs remained planted underground from September through May and could only be lifted, inspected, and delivered during the brief summer dormancy window in June and July. By late 1634 and 1635, however, professional florists and textile artisans in Haarlem, Amsterdam, Alkmaar, Enkhuizen, and Utrecht began trading non-standardized paper forward contracts year-round. Excluded from the official Koopmansbeurs, traders organized informal fraternal clubs called collegia that met several times a week in back-room taverns. Transactions were priced by the aas (1/20th of a gram, approximately 0.048 grams) for rare offset bulbs, or by the pound and hundred-bulb batch (pondgoed) for common unstreaked tulips. Using auction methods such as in het ootjen (descending and ascending bid auctions) and sealed-slate bargaining, buyers and sellers toasted each completed contract with a statutory cash commission called wijnkoop (“wine money”), capped at three stuivers per guilder up to a maximum of three guilders per trade, which paid for tavern food, beer, tobacco, and small gratuities.
From Forward Bubble to the February 1637 Options Conversion
As bubonic plague swept through Holland between 1635 and 1637—killing nearly one-seventh of Amsterdam’s and Haarlem’s populations and creating acute labor shortages that drove up urban artisans’ nominal wages and inheritance windfalls—speculation in the tavern collegia accelerated dramatically. In November 1636, prices for rare broken varieties dipped briefly when news arrived that German Protestant princes had suffered military setbacks, cutting off luxury export demand, but speculators rapidly pivoted into common mass bulbs (Switsers, Witte Croonen, and Gouda) sold by weight.
What transformed a localized luxury craze into an explosive winter price spike between late November 1636 and February 3, 1637 was a structural shift in contract terms. As economic historians Earl Thompson, Larry Neal, and Marc Weidenmier have documented, ruinous autumn price swings prompted prominent Dutch tulip growers and buyers to lobby municipal magistrates to convert binding forward purchase commitments into option-like contracts. In late November 1636, delegates of the regional florists’ guilds began drafting a proposal allowing any buyer of a future tulip bulb for June 1637 delivery to walk away from the contract by paying the seller a small fixed penalty (rouwkoop, or “regret money”). Once tavern traders anticipated that downside losses would be legally capped at a few percent of the strike price while upside gains remained unlimited, rational speculators bid nominal contract strike prices to astronomical heights with zero money down.
Between December 1636 and the first week of February 1637, the index of common bulb contract prices surged nearly twentyfold. At an orphan charity auction in Alkmaar on February 5, 1637, ninety-nine lots of rare and common tulips fetched an astonishing 90,000 guilders—at a time when a skilled Amsterdam master carpenter earned roughly 250 to 300 guilders a year and a prime canal house cost 10,000 guilders. A single 200-azen bulb of the prized Admirael van Enckhuysen with an offset sold for 5,200 guilders, while a rare Semper Augustus bulb was quoted between 5,500 and 6,000 guilders.
Just two days earlier, however, on Tuesday, February 3, 1637, routine tavern bidding at a Haarlem collegium had abruptly stalled when no buyer agreed to pay the inflated asking prices for pound-goods bulbs. Within forty-eight hours, tavern secondary markets froze across Holland. On February 24, 1637, an assembly of delegates from the major Dutch florists’ guilds meeting in Amsterdam signed a formal resolution stipulating that all tulip forward contracts written after November 30, 1636 could be unilaterally canceled by the buyer in March 1637 upon payment of a 10 percent compensation fee to the seller. When the States of Holland and West Friesland declined to enforce the contracts on April 27, 1637—suspending all tulip debt litigation and tossing resolution back to local town magistrates—the city of Haarlem capped the cancellation settlement fee at just 3.5 guilders per 100 guilders of contract value (3.5 percent) in May 1638.
Aftermath: Institutional Separation of Core Trade and Speculation
Because the States of Holland and municipal arbitration panels (commissarissen van de bloemzaken) effectively converted post-November 1636 forward obligations into 3.5-percent call options and relied on the 1610 windhandel doctrine to shield tavern speculators from debtor’s prison, the collapse of the tulip derivatives market triggered almost no commercial bankruptcies among Amsterdam’s major merchant houses. Not a single guilder of the Amsterdamsche Wisselbank‘s bullion reserves was impaired, and Baltic rye shipments at the Damrak Korenbeurs continued without interruption throughout the spring of 1637. By walling off uncollateralized tavern derivatives from its core metallic clearing bank and physical grain reserves, the Dutch Republic survived history’s first recorded options bubble with its real economy and sovereign credit wholly intact.
Theoretical & Balance-Sheet Transmission Mechanism
In the Kindleberger–Minsky taxonomy of financial instability (Kindleberger, 1978; Minsky, 1986) and Irving Fisher’s (1933) debt-deflation framework, speculative asset booms become systemic crises when credit expansion shifts balance sheets from hedge finance (cash flows covering principal and interest) to speculative and Ponzi finance (relying on rising asset prices and short-term margin roll-overs).
Once monetary tightening or an exogenous shock halts price appreciation, forced margin liquidations trigger Fisherian debt-deflation: fire-sale asset discounts erode bank collateral values, contracting credit supply across the real economy.
Sources and Further Reading
- J. G. van Dillen, “Bronnen tot de Geschiedenis van den Oostzeehandel (1588–1625),” Huygens Institute / Royal Netherlands Academy of Arts and Sciences (KNAW), 1934. Historical & Financial Reference
- Nederlandsch Economisch-Historisch Archief (NEHA), “NEHA en de Geschiedenis van de Amsterdamse Beurs en Prijscouranten,” International Institute of Social History (IISH), 2019. Historical & Financial Reference
- Stephen Quinn and William Roberds, “How Amsterdam Got Fiat Money,” Federal Reserve Bank of Chicago / Federal Reserve Bank of Atlanta, 2010. Central Bank / Monetary Authority
- William Roberds and François R. Velde, “Early Public Banks (Working Paper No. 2014-9),” Federal Reserve Bank of Atlanta / EconStor, 2014. Central Bank / Monetary Authority
- Museum of the Amsterdam Stock Exchange, “The Tulip Mania (1636–1637),” Stichting Capital Amsterdam / Beursgeschiedenis, 2020. Historical & Financial Reference
- Larry Neal and Marc D. Weidenmier, “Crises in the Global Economy from Tulips to Today: Contagion and Consequences,” National Bureau of Economic Research (NBER), 2003. Peer-Reviewed / Academic Research
- Irving Fisher — "The Debt-Deflation Theory of Great Depressions," Econometrica 1, no. 4 (FRASER Federal Reserve Archive, 1933): 337–357 Central Bank / Monetary Authority
- Charles P. Kindleberger & Robert Z. Aliber — Manias, Panics, and Crashes: A History of Financial Crises (Palgrave Macmillan) Peer-Reviewed / Academic Research
Cite This Historical Dossier (APA / Chicago)
APA (7th ed.): Ç., S. (Ed.). (2026). Amsterdam's Korenbeurs Grain Trade, the Wisselbank Agio, and the 1637 Tulip Crash. In Forgotten Fortunes Historical Monograph Series (Forgotten Fortunes Editorial Desk). https://forgottenfortunes.net/amsterdam-tulip-mania-grain-trade/
MLA (9th ed.): Ç., Soner, ed. "Amsterdam's Korenbeurs Grain Trade, the Wisselbank Agio, and the 1637 Tulip Crash." Forgotten Fortunes: Financial & Monetary History Archive, 2026, https://forgottenfortunes.net/amsterdam-tulip-mania-grain-trade/.
Chicago (17th ed.): Ç., Soner, ed. "Amsterdam's Korenbeurs Grain Trade, the Wisselbank Agio, and the 1637 Tulip Crash." Forgotten Fortunes Historical Monograph Series (Forgotten Fortunes Editorial Desk), September 20, 2026. https://forgottenfortunes.net/amsterdam-tulip-mania-grain-trade/.
Have an idea for another financial history documentary or article? Request a story →