In This Article
Over the three decades following the entry into force of the North American Free Trade Agreement (NAFTA) on January 1, 1994, the fiscal and financial architecture of the Mexican state was repeatedly reshaped by armed insurgency, natural disasters, and internal security campaigns. That transformation unfolded across three distinct milestones in sovereign risk and military-public finance. It began on New Year’s Day 1994, when the Zapatista National Liberation Army (EZLN) uprising in Chiapas and the subsequent assassination of presidential candidate Luis Donaldo Colosio triggered more than US$10 billion in capital flight, prompting the Treasury to swap peso-denominated Cetes for dollar-indexed Tesobonos on the eve of the Tequila Crisis. It continued with the 1996 creation of Mexico’s Natural Disaster Fund (FONDEN) and the 2006 launch of CatMex—the world’s first sovereign parametric catastrophe bond—followed by the World Bank MultiCat Mexico program that paid out US$150 million after the September 2017 earthquakes. Finally, following the post-2006 internal security mobilization and the 2020 dissolution of FONDEN, the Ministry of National Defense (SEDENA) evolved into Mexico’s dominant public infrastructure contractor and state enterprise operator. [1]

January 1, 1994: The Chiapas Uprising, Colosio, and the Tesobono Trap
Throughout 1993, President Carlos Salinas de Gortari and Finance Minister Pedro Aspe presented Mexico to international bondholders as an emerging-market triumph. Inflation had fallen below single digits, state enterprises had been privatized, the Banco de México had been granted constitutional autonomy, and the U.S. Congress had ratified NAFTA in November 1993. Yet beneath the veneer of stability lay a fragile external imbalance: Mexico’s semi-fixed exchange-rate band (which allowed the peso to depreciate by only four ten-thousandths of a nuevo peso per day against the dollar) had produced an overvalued currency and a current-account deficit approaching 7 percent of gross domestic product, financed overwhelmingly by volatile foreign portfolio inflows into short-term peso Treasury bills (Certificados de la Tesorería, or Cetes). [2]
In the predawn hours of January 1, 1994—the exact day NAFTA took effect—several thousand indigenous insurgents of the Ejército Zapatista de Liberación Nacional (EZLN), led publicly by Subcomandante Marcos, seized San Cristóbal de las Casas and three other municipal seats in the southern state of Chiapas, declaring war on the federal army and denouncing NAFTA. Although twelve days of combat between SEDENA brigades and the EZLN gave way to a ceasefire and peace talks at the San Cristóbal Cathedral, the armed rebellion shattered the illusion of seamless political modernization. [3]
Eleven weeks later, on March 23, 1994, Institutional Revolutionary Party (PRI) presidential candidate Luis Donaldo Colosio was assassinated at a campaign rally in Lomas Taurinas, Tijuana. Together, the Chiapas rebellion, the Colosio assassination, rising U.S. Federal Reserve interest rates, and the September 1994 murder of PRI Secretary General José Francisco Ruiz Massieu set off waves of institutional capital flight. Between mid-February and late April 1994 alone, the Banco de México lost more than US$10 billion in international reserves—falling from nearly US$29 billion to roughly US$17 billion—as foreign mutual funds and Mexican treasurers dumped peso Cetes. [4]
Rather than widen the exchange-rate band or let domestic interest rates spike high enough to choke the economy in an election year, Mexican authorities engineered a fateful debt swap. The Treasury and Banco de México aggressively retired peso-denominated Cetes and replaced them with Tesobonos—short-term zero-coupon sovereign bills payable in pesos but indexed 100 percent to the U.S. dollar exchange rate. Between January and November 1994, outstanding Tesobonos exploded nearly tenfold, from roughly US$3.1 billion to over US$29 billion, while central bank reserves fell toward US$6 billion after renewed fighting threats in Chiapas in December 1994. When the incoming administration of Ernesto Zedillo attempted a 15 percent widening of the currency band on December 20, 1994, creditors refused to roll over maturing Tesobonos, forcing a free float of the peso and an emergency US$50 billion international rescue package led by the U.S. Treasury and the International Monetary Fund. [5]
| Documented Figure / Metric | Historical Significance & Archival Context |
|---|---|
| US$4 billion | When the magnitude 8.0 earthquake devastated Mexico City in September 1985—causing roughly US$4 billion in direct physical damage—the federal government had no dedicated reconstruction reserve, forcing painful mid-year budget reallocations from social and infrastructure programs. |
| US$800 million | Under the Federal Budget and Fiscal Responsibility Law, the Ministry of Finance and Public Credit (SHCP) was legally mandated to allocate at least 0.4 percent of programmable federal expenditure—approximately US$800 million annually—to FONDEN and its preventive counterpart, FOPREDEN. |
From Fiscal Scrambling to FONDEN (1996)
The 1994–1995 crisis forced Mexican fiscal policymakers to confront another chronic source of budget destabilization: catastrophic natural disasters. Sitting astride the Cocos-North American subduction zone and bordered by both Atlantic and Pacific hurricane basins, Mexico had suffered devastating fiscal shocks whenever major earthquakes or tropical cyclones struck. When the magnitude 8.0 earthquake devastated Mexico City in September 1985—causing roughly US$4 billion in direct physical damage—the federal government had no dedicated reconstruction reserve, forcing painful mid-year budget reallocations from social and infrastructure programs. [6]
To end ad-hoc post-disaster budget raids, the Zedillo administration established the Fondo de Desastres Naturales (FONDEN) inside the federal budget in 1996, making it fully operational in 1999 through a trust managed by the state development bank Banobras. Under the Federal Budget and Fiscal Responsibility Law, the Ministry of Finance and Public Credit (SHCP) was legally mandated to allocate at least 0.4 percent of programmable federal expenditure—approximately US$800 million annually—to FONDEN and its preventive counterpart, FOPREDEN. Whenever a hurricane or earthquake exceeded local municipal capacity, FONDEN financed 100 percent of emergency rehabilitation of federal roads, bridges, hospitals, and schools, and up to 50 percent of state-level infrastructure. [7]
CatMex (2006) and World Bank MultiCat Mexico: The $150M Earthquake Payout
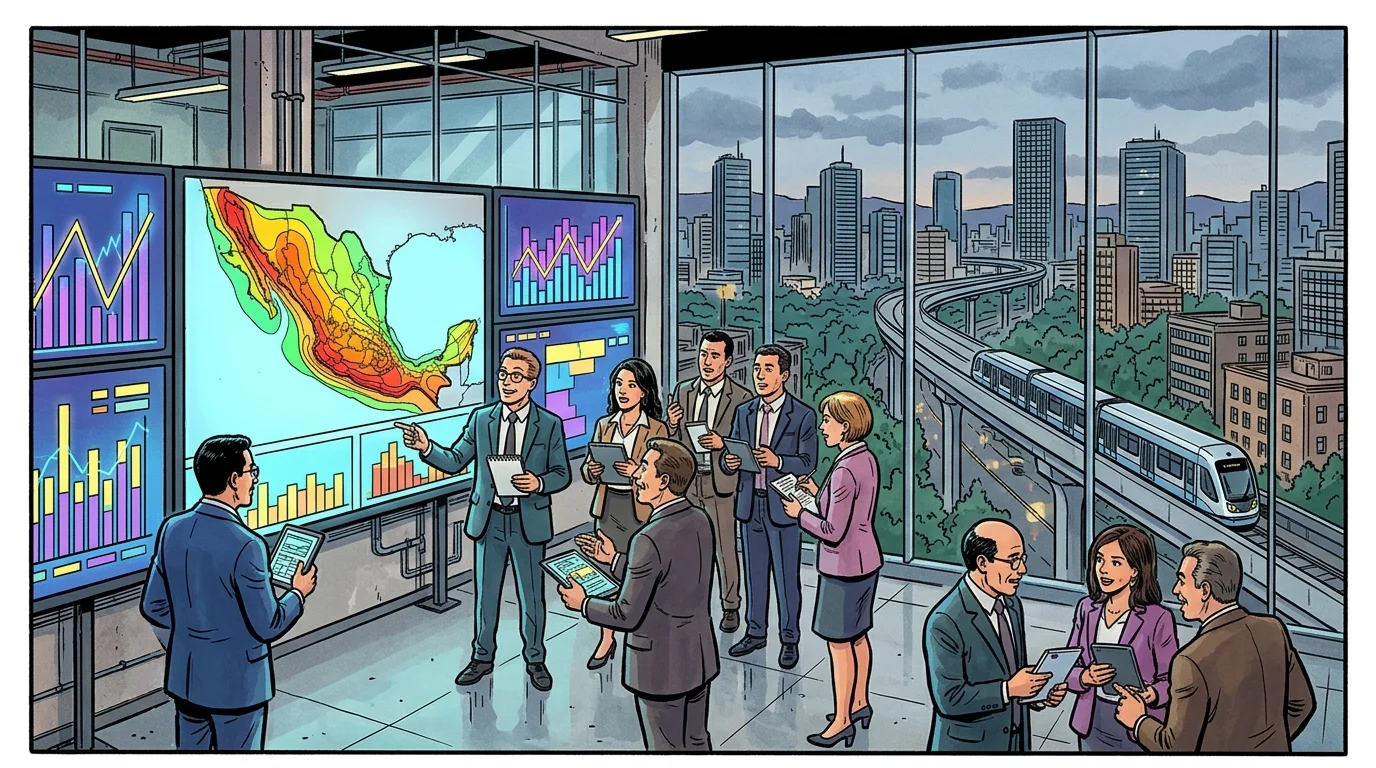
As FONDEN’s reconstruction liabilities grew, SHCP risk managers and the World Bank Treasury pioneered an unprecedented sovereign risk-transfer strategy: shifting peak tail risk directly onto global capital markets via parametric catastrophe bonds. Unlike traditional indemnity insurance, which requires months or years of physical loss adjustment before paying claims, a parametric cat bond triggers an automatic payout within days if an independent scientific agency—such as the U.S. National Hurricane Center or the U.S. Geological Survey—records an earthquake magnitude or hurricane central barometric pressure exceeding pre-agreed physical thresholds inside specified geographic boxes.
In May 2006, Mexico and FONDEN sponsored CatMex Ltd., a US$160 million three-year parametric earthquake bond (paired with US$290 million in parametric reinsurance), becoming the first sovereign government in financial history to issue a catastrophe bond. Building on CatMex’s success, Mexico partnered with the World Bank in October 2009 to launch MultiCat Mexico 2009—a US$290 million multi-peril cat bond covering earthquakes across three seismic zones and hurricanes along both the Pacific and Atlantic coasts. Successor issuances followed with a US$315 million MultiCat Mexico 2012 bond (which paid out US$50 million after Hurricane Patricia struck Jalisco in October 2015 as the strongest tropical cyclone ever recorded in the Western Hemisphere) and a US$360 million World Bank IBRD Capital-at-Risk note series issued for FONDEN in August 2017. [8]
Just weeks after the August 2017 bond closed, on September 7, 2017, a catastrophic magnitude 8.2 earthquake struck offshore Chiapas near Tehuantepec, followed twelve days later by a deadly magnitude 7.1 earthquake near Puebla and Mexico City. Because the Chiapas tremor’s epicenter and magnitude breached the exact parametric box thresholds of the Class A notes, the World Bank catastrophe bond triggered a full 100 percent principal payout of US$150 million to FONDEN within weeks—delivering immediate hard-currency reconstruction liquidity at zero fiscal debt cost.
Post-2006 Security Budgets and SEDENA’s Infrastructure Portfolio
Parallel to its disaster-finance innovations, Mexico’s federal budget underwent a profound shift toward military expenditure and military-operated state enterprises. Following President Felipe Calderón’s December 2006 deployment of federal armed forces against drug trafficking organizations, combined annual appropriations for the Ministry of National Defense (SEDENA) and the Ministry of the Navy (SEMAR) expanded steadily in real terms to finance troop deployments, intelligence, airlift, and regional military hospitals.
After taking office in December 2018, President Andrés Manuel López Obrador radically expanded the economic role of the armed forces while dismantling autonomous civilian trusts—formally extinguishing FONDEN’s trust structure in October 2020 and returning disaster appropriations to centralized Treasury management. Citing the speed, discipline, and insulation from private-contractor graft of SEDENA’s Directorate General of Engineers, the federal government transferred Mexico’s largest capital infrastructure projects directly to military execution and ownership. Between 2019 and 2024, SEDENA built and assumed corporate ownership—via the military holding group Olmeca-Maya-Mexica—of the Felipe Ángeles International Airport (AIFA) north of Mexico City, major sections and the commercial operation of the 1,554-kilometer Tren Maya railway across the Yucatán Peninsula, the revived state airline Mexicana de Aviación, dozens of regional airports, and the administration of Mexico’s land and maritime customs agencies, transforming the defense ministry into a central pillar of Mexican public investment.
Theoretical & Balance-Sheet Transmission Mechanism
In the Kindleberger–Minsky taxonomy of financial instability (Kindleberger, 1978; Minsky, 1986) and Irving Fisher’s (1933) debt-deflation framework, speculative asset booms become systemic crises when credit expansion shifts balance sheets from hedge finance (cash flows covering principal and interest) to speculative and Ponzi finance (relying on rising asset prices and short-term margin roll-overs).
Once monetary tightening or an exogenous shock halts price appreciation, forced margin liquidations trigger Fisherian debt-deflation: fire-sale asset discounts erode bank collateral values, contracting credit supply across the real economy.
Sources and Further Reading
- Eduardo Turrent Díaz, “El despegue que se frustró: 1994 (Historia del Banco de México, Tomo XIX),” Banco de México, 2015. Central Bank / Monetary Authority
- Banco de México, “Monetary Policy, Exchange Rate Regime, and Financial Stability in Mexico Since 1994,” Banco de México Working Papers, 2015. Central Bank / Monetary Authority
- World Bank Treasury, “Case Study: Transferring Mexico’s Disaster Risk to the Capital Markets (FONDEN, CatMex, and MultiCat Mexico),” World Bank Group, 2020-03-04. International Financial Institution
- World Bank and Secretaría de Hacienda y Crédito Público, “FONDEN: Mexico’s Natural Disaster Fund—A Review,” World Bank Open Knowledge Repository, 2012. International Financial Institution
- World Bank Disaster Risk Financing and Insurance Program, “Sovereign Catastrophe Bonds in Mexico and the Pacific Alliance: The 2017 Earthquake Payout,” World Bank Group, 2019-04-01. International Financial Institution
- BNamericas Infrastructure Intelligence, “Mexico to Double Rail Spending Over Roads: SEDENA, Tren Maya, and Federal Infrastructure Budgets,” BNamericas, 2024. Historical & Financial Reference
- Irving Fisher — "The Debt-Deflation Theory of Great Depressions," Econometrica 1, no. 4 (FRASER Federal Reserve Archive, 1933): 337–357 Central Bank / Monetary Authority
- Charles P. Kindleberger & Robert Z. Aliber — Manias, Panics, and Crashes: A History of Financial Crises (Palgrave Macmillan) Peer-Reviewed / Academic Research
Cite This Historical Dossier (APA / Chicago)
APA (7th ed.): Ç., S. (Ed.). (2026). Chiapas 1994 Capital Flight, Sovereign Catastrophe Bonds, and SEDENA's Empire. In Forgotten Fortunes Historical Monograph Series (Forgotten Fortunes Editorial Desk). https://forgottenfortunes.net/mexico-fonden-catastrophe-bonds/
MLA (9th ed.): Ç., Soner, ed. "Chiapas 1994 Capital Flight, Sovereign Catastrophe Bonds, and SEDENA's Empire." Forgotten Fortunes: Financial & Monetary History Archive, 2026, https://forgottenfortunes.net/mexico-fonden-catastrophe-bonds/.
Chicago (17th ed.): Ç., Soner, ed. "Chiapas 1994 Capital Flight, Sovereign Catastrophe Bonds, and SEDENA's Empire." Forgotten Fortunes Historical Monograph Series (Forgotten Fortunes Editorial Desk), September 20, 2026. https://forgottenfortunes.net/mexico-fonden-catastrophe-bonds/.
Have an idea for another financial history documentary or article? Request a story →